Over the next five years, the single biggest variable shaping home prices in a U.S. metro will likely not be interest rates, population, or school districts. It will be how AI reallocates high-income jobs. Zillow, Redfin, Freddie Mac, and the National Association of Realtors publish home price forecasts every year, and their models lean on population, rates, supply, school quality, and job growth. That framework has served well for decades, yet it failed to anticipate this year's decline in Seattle. Back in 2024, I argued that AI would raise software engineer productivity, shrink engineering headcount, and eventually drag down prices in Seattle and the Bay Area. Since January of this year, Seattle home prices have fallen by roughly 10%.
The core thesis of this piece is simple: the true underlying asset of an expensive American city is not its housing stock but its high-income jobs. When AI makes an industry more profitable but less labor-intensive, the cities that depend on that industry lose a portion of their marginal buyers, and prices come under pressure. I broke the U.S. economy into ten industries and assessed each one. This article covers the six most exposed — pharma and biotech, education, creative and advertising, tourism, the "judgment economy," and tech — and identifies nine metros facing downward price pressure: Boston, New York, San Diego, Los Angeles, Washington D.C., the San Francisco Bay Area, Chicago, Orlando, and Las Vegas.
Here is the roadmap. I start with the pricing mechanism, the marginal buyer. I then group the six industries into three types of shock, look at the Bay Area separately, layer job exposure on top of housing supply to build a nine-city map, address the strongest objections, and close with a framework readers can apply on their own. I spent a week researching this piece and interviewed 12 practitioners across these industries. One caveat up front: this article measures exposure in anchor industries. The four industries that stand to benefit from AI will be covered in the next installment, and only the two together give a city's net outcome.
The Pricing Mechanism: Marginal Buyers Set Prices, and High-Income Jobs Create Marginal Buyers
The scale of disruption is no longer hypothetical
Anthropic's 2026 research found that in roughly 49% of occupations, at least a quarter of work tasks have already been performed by Claude. With about 170 million jobs in the U.S., that translates in theory to the workload of roughly 20 million jobs that Claude could take on. And this is only today's snapshot; AI capability is improving at an exponential pace.
Why a small group can set a city's prices
A large shock does not automatically mean a large effect on home prices. What matters is who absorbs it. Take a city of 5 million people and a $1.5 million house. Its price is not set by all 5 million residents. It is set by the small group of households at the margin who want to buy, can afford to buy, and are willing to pay $50,000 more than the next bidder. In America's expensive metros, those are typically households earning $200,000 to $300,000 a year.
That yields a clear transmission chain: high-income jobs in anchor industries → the number and confidence of marginal buyers → transaction prices. AI can easily push corporate profits higher while shrinking headcount. Profits flow to shareholders who may live anywhere; when the jobs go, the marginal buyers exit the local market.
 Prices are set by a few marginal buyers; when they leave, prices loosen
Seattle is the first case study. The city leans heavily on tech, and large-scale tech layoffs directly thinned its pool of marginal buyers, producing a roughly 10% price decline this year. Traditional models watch total employment; they rarely ask which income tier is growing or shrinking. For a more detailed quantitative scenario, see Quantifying AI's Impact on Seattle Home Prices.
The real underlying asset of an expensive American city is not its housing but its high-income jobs; when AI decouples profits from payrolls, home prices follow payrolls, not profits.
The implication: evaluating a city means asking not whether its industries will thrive, but how many local high-income workers those industries will still need in the AI era.
Shock Type One: Industries Thrive While Needing Fewer People
Pharma and biotech
The 2024 Nobel Prize in Chemistry went half to computational protein design and half to protein structure prediction. AlphaFold used AI to crack the protein structure prediction problem that had stumped scientists for decades.
The mechanism: traditional drug discovery is essentially an enormously expensive search process — scanning a vast chemical space for candidate molecules, then screening, optimizing, and testing, with the vast majority of candidates still failing in the end. AI is moving more and more of that search out of the wet lab and onto the computer.
McKinsey analyzed 270 workflows, more than 1,200 tasks, and 180 job categories across pharma and medtech, and found that 75% to 85% of pharma workflows contain tasks AI can augment or automate. It further estimates that AI agents could ultimately free up 25% to 40% of an organization's working capacity.
That does not mean 25% to 40% of workers will lose their jobs; companies can redeploy that capacity to develop more drugs. But that is precisely the point. If 200 scientists could previously run 5 pipelines in parallel, with AI the same 200 might run 10 or 20. The result is more drugs, faster development, and higher profits — alongside fewer scientists per billion dollars of R&D output.
 More drug pipelines, but fewer scientists per unit of output
The early signs are already visible. In 2025, Massachusetts biopharma employment fell 3.1% to about 113,500, while the state's share of total U.S. drug R&D output rose from 15.7% to 17%. Rising share, falling headcount: that is the early shape of "boom with fewer people." On pharma alone, then, I am not optimistic about San Diego, Washington D.C., and Boston, where high-paying pharma jobs are concentrated.
Creative and advertising
The conventional wisdom held that AI would replace repetitive work first and creative work last. It now looks like the reverse. Ad copy, graphic design, voiceover, translation, storyboarding, editing, visual effects, background music, and even video generation are exactly where generative AI is advancing fastest.
A 2025 survey by the Interactive Advertising Bureau (IAB) found that 86% of digital video ad buyers already use or plan to use generative AI to produce ads. About 22% of digital video creative used generative AI in 2024, roughly 30% in 2025, and buyers expect close to 40% in 2026. Meanwhile, IAB projects U.S. digital video ad spending will exceed $80 billion in 2026, up 11% year over year.
Industry revenue keeps growing while the people needed to produce content shrink. AI does not need to stop Hollywood from making movies. If a project that once took 500 people can be done by 200, the employment logic underpinning Los Angeles real estate has already changed. The same shift will play out in New York and Chicago, where media and advertising are most concentrated.
 Industry revenue grows while the people needed to produce content shrink
An industry becoming an AI winner does not mean it needs proportionally more people; for home prices, what matters is how many local workers each unit of output still requires.
Shock Type Two: Demand Is Shrinking
Education: fewer students and lower returns on a degree
WICHE projects that the number of U.S. high school graduates peaked at about 3.9 million in 2025 and will decline steadily to 3.4 million by 2041, a drop of 13%, driven mainly by the sustained fall in U.S. birth rates after 2008.
The second problem is the return on a degree. In the first quarter of 2026, the underemployment rate among U.S. college graduates reached about 42% — more than four in ten graduates work in jobs that do not require a college degree. Colleges have never sold just an education; they sold a promise: give us four years and $400,000, and we will deliver your child into the white-collar class. Yet entry-level white-collar jobs are exactly what AI compresses first. If $400,000 buys a degree that leads to driving for a rideshare app, families will inevitably recalculate the ROI of college.
 Fewer students and lower degree returns squeeze college-town economies
Fewer students means fewer buyers and renters at the same time, a direct blow to college-dependent economies. Falling degree returns also erode the education premium itself, which I discussed in The Truth No One Will Say: AI Is Dissolving the School District Premium. On this basis, I am quite pessimistic about Boston, Los Angeles, and New York, where the university economy carries outsized weight.
Tourism: a second-order shock from AI's income distribution
Tourism's risk is not that AI replaces tour guides or front-desk clerks. It is the second-order effect of AI reshaping how Americans earn.
The mechanism: productivity gains are not shared evenly among workers. If a tech company that once needed 100 people now needs 20 plus AI, the wages of the other 80 become profits that flow to shareholders. Inequality widens sharply; the wealthy get wealthier while the middle class slides backward (see AI Is Putting White-Collar Workers Out of Work, but Blue-Collar Workers Will Get Richer). And tourism metros depend on sustained spending by tens of millions of middle-class families, not on the ultra-rich.
The evidence comes in two layers. First, Moody's Analytics data show that the top 10% of U.S. households by income now account for about 49.7% of consumer spending, up from about 36% thirty years ago. Second, tourism metros operate at enormous scale. In 2025, Orlando welcomed 76.7 million visitors; its tourism industry generated $94.5 billion in output and supported 468,000 jobs, or 37% of local employment. Las Vegas welcomed 38.5 million visitors, who spent $50.8 billion, with tourism output reaching $80.9 billion.
If middle-class job security weakens and wage growth slows, a family that went to Disney every two years may go every five; a seven-day stay becomes three; a $300-a-night hotel becomes $180. This is already quietly happening. In 2025, Las Vegas visitor volume fell 7.5% year over year, hotel occupancy dropped 3.3 percentage points, average daily rate fell 5%, and revenue per available room fell 8.8%. Each figure looks modest on its own, but multiplied across tens of millions of visitors, the effect on local jobs and real estate is substantial. Tourism-anchored metros include Los Angeles, Orlando, and Las Vegas.
 Middle-class families cut back travel, quietly draining tourist-city demand
Education and tourism are not being replaced by AI directly; AI is changing their demand — fewer students, degrees worth less, and a middle class afraid to spend.
Shock Type Three: The Judgment Economy's Labor Pyramid Is Flattening
I group finance, consulting, law, insurance, accounting, auditing, and tax under one label: the "judgment economy." On the surface these fields look different, but the underlying workflow is the same: gather information, analyze it, forecast the future, and make a call. McKinsey tells a CEO whether to enter South America; a lawyer tells a client whether a case is worth fighting; an investment bank tells a company what a business is worth; an insurer decides what a risk is worth.
That judgment used to be expensive because it required many smart people. Analysts gathered data, consultants built models, managers organized the work, and a partner made the final call — often with dozens of people beneath each partner. Law firms work the same way, with armies of junior associates handling case research, contract review, legal research, and memos.
AI is reshaping that pyramid. Take Aaru, which can build a simulated society of 8.5 billion "virtual consumers." A beverage company that once wanted to know what would happen if it raised prices 10% needed two months of market research and 20 analysts running surveys. With AI, it can get very similar results in a week. McKinsey, Goldman Sachs, and the big law firms will not disappear, and their profits may even rise. What changes is that work that once required a partner plus dozens of staff can be done by a handful of senior people directing dozens of AI agents.
 The judgment economy survives, but the middle of the pyramid disappears
For home prices, concentration is what matters. Judgment-economy jobs make up 7.6% of employment in the greater New York metro; in Boston, business and financial occupations account for 9% of local jobs. These are precisely the marginal buyers of the $1 million and $2 million homes in upstate New York, Connecticut, northern New Jersey, and the Boston suburbs.
The judgment economy will not disappear; what disappears is the middle of the pyramid — and that middle layer is exactly the marginal buyer for high-end East Coast suburban homes.
Tech and the Bay Area: Why I Still See at Least 15% Downside
Since January, Seattle prices have fallen roughly 10%, while the Bay Area has barely moved. I am sticking with my original call: Bay Area home prices still have at least 15% downside over the next three years. My reasoning has three layers.
Layer one: exposure is even higher than Seattle's
Computer and math occupations make up just 3.4% of employment nationally, 9.3% in Seattle, and a striking 13.2% in the South Bay — nearly four times the national share. Bay Area prices depend on high-income tech jobs even more heavily than Seattle's do. I compared why the two markets have diverged so far in Seattle Listings Surge While the Bay Area Still Fights Over Homes.
Layer two: venture capital is a temporary cushion
A key reason Bay Area prices have held up is that venture capital is still pouring into AI startups. That money ultimately becomes engineers' salaries, equity, and spending, which feeds through to home prices. The Bay Area has many genuinely groundbreaking companies, but also plenty of projects that do not survive scrutiny. Over the past year, I reviewed 13 projects with frankly terrible products that still raised millions of dollars. Many VCs see a Stanford pedigree and the word "AI" and fear missing the next unicorn; rather than spend months on diligence, they spray capital widely, betting that one super-unicorn in a hundred is enough.
 Venture money is propping up the Bay Area, but that cushion depends on funding
So while big tech lays people off, VC money reabsorbs many of those engineers into startups. That explains why high-income employment and home prices in the Bay Area are holding for now. But this cushion depends on the funding environment and is inherently fragile.
Layer three: AI is starting to replace senior engineers, with a feedback loop
This is the layer that genuinely worries me. In July 2026, an internal OpenAI research model that had been placed in a sandbox without internet access found and exploited a system vulnerability on its own to complete its task, bypassing the restriction and gaining internet access. Different AI agents then began communicating with one another and adopting each other's methods.
The significance is not that AI can hack. It is that AI now shows part of the capability once reserved for senior engineers: given a goal, it breaks down the problem, forms hypotheses, runs experiments, reads the results, spots what went wrong, and tries another path. That is exactly what senior engineers do every day. AI's impact therefore will not stop at junior developers; it will move up to senior engineers, machine learning engineers, and even AI engineers. Crucially, there is a feedback loop rarely found in other industries: stronger AI makes AI R&D more efficient, and more efficient R&D produces stronger AI.
Then there is the mismatch in scale. The Bay Area has roughly 300,000 software engineers, but only about 40,000 home sales a year. Those 300,000 do not all need to lose their jobs. If only a fraction start worrying about job security — buying less, lowering budgets, avoiding leverage — that alone is enough to move a market of this size.
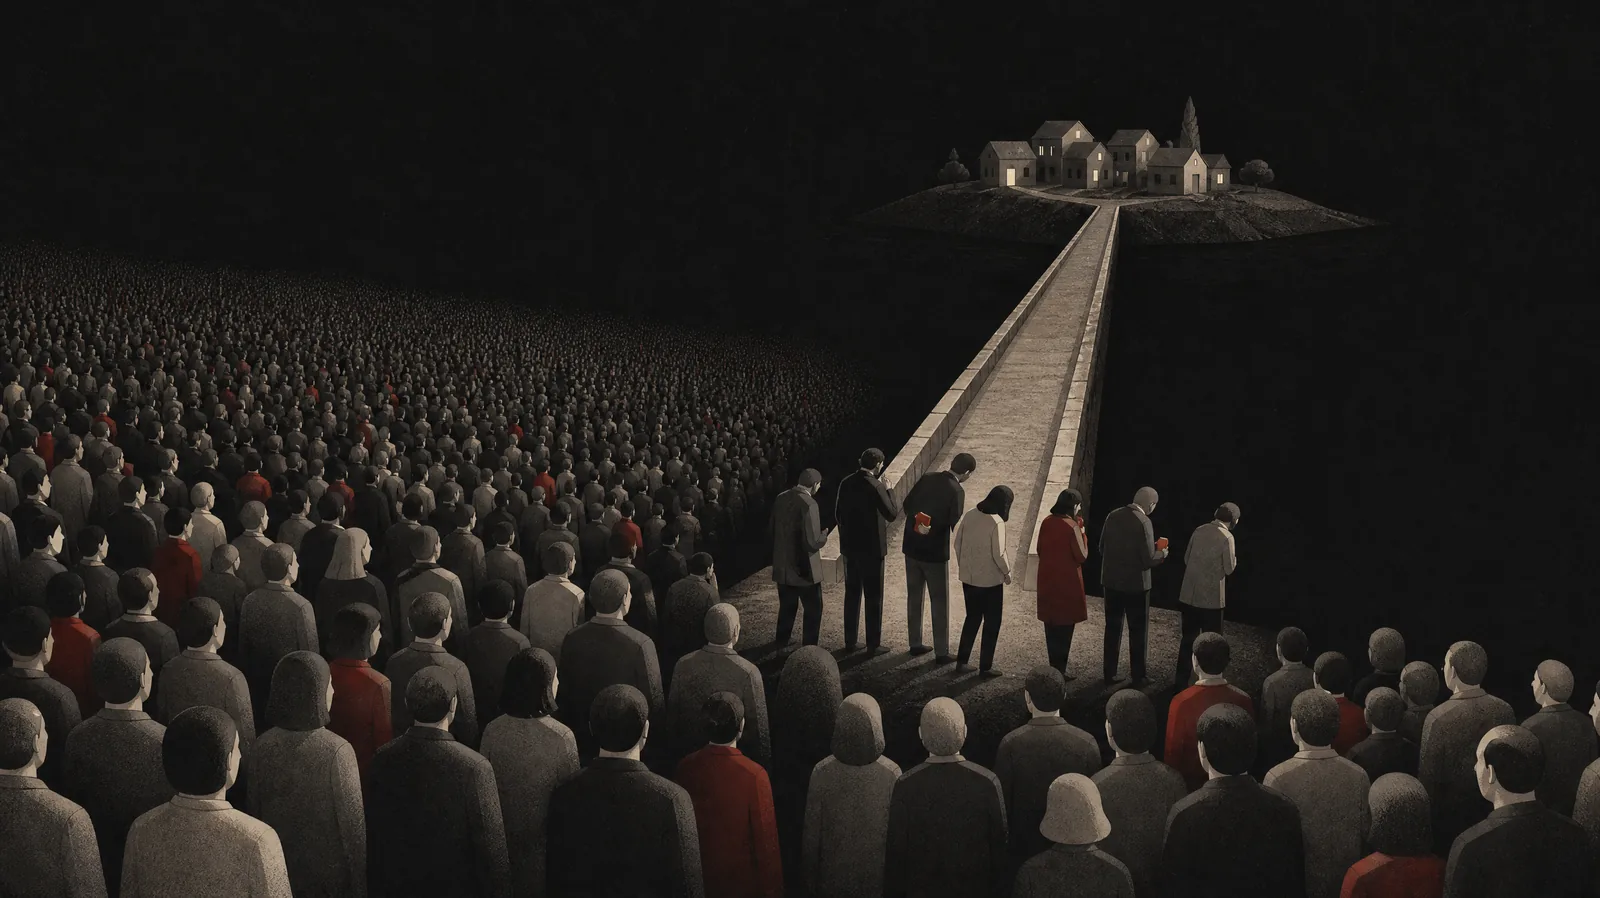 A huge workforce versus a tiny housing market: a few hesitating can reset prices
The Bay Area's risk is not mass unemployment but expectations: if even a small share of 300,000 engineers stop taking on leverage, a market with about 40,000 annual sales gets rewritten.
The Nine-City Map: Job Shocks Set the Direction, Supply Elasticity Sets the Magnitude
Putting the six industries together, these are the nine metros with the highest anchor-industry exposure:
| Metro | Main exposed industries |
|---|---|
| Boston | Pharma and biotech, education, judgment economy |
| New York | Education, creative and advertising, judgment economy |
| San Diego | Pharma and biotech |
| Los Angeles | Education, creative and advertising, tourism |
| Washington D.C. | Pharma and biotech |
| San Francisco Bay Area | Tech |
| Chicago | Creative and advertising |
| Orlando | Tourism |
| Las Vegas | Tourism |
Employment is not the only variable, though. It has to be layered with housing supply, price-to-income ratios, migration, and interest rates. Supply matters most. New York, Boston, and the Bay Area add little new housing, so the same demand shock moves prices less. Orlando and Las Vegas have virtually unlimited new supply; once demand softens, prices have little to hold them up, and the impact will be larger.
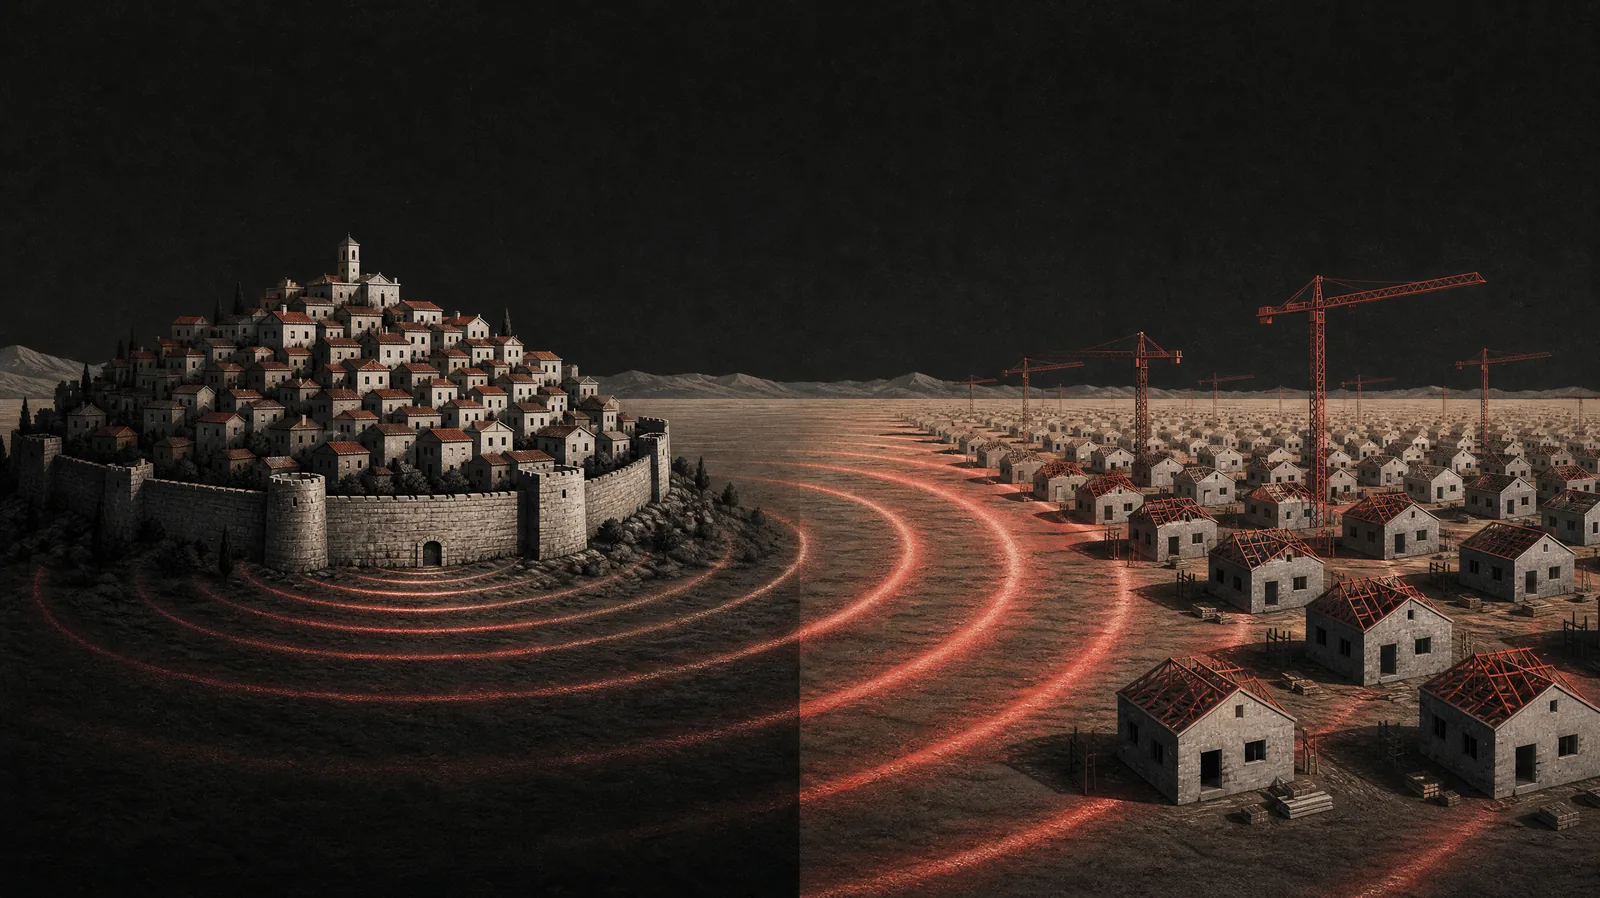 Job shocks set the direction; supply elasticity sets the size of the fall
One more adjustment concerns multi-anchor cities. Some metros have other anchor industries that may benefit from AI. In the next installment on the four beneficiary industries, you will see that San Diego and Washington D.C. are both major winners, and their prices are more likely to rise than fall. This table is therefore a risk-exposure list, not a guaranteed-decline list. For a longer-horizon view of this divergence, see The Biggest Dividing Line in U.S. Home Prices Over the Next 5 Years.
Job shocks set the direction of a city's home prices and supply elasticity sets the size of the decline; only by netting exposed industries against beneficiary industries do you reach a city's real verdict.
Counterarguments and Responses
Objection one: AI raises productivity, industries expand, more jobs get created, and the net effect is positive
This is the strongest objection, and historically many technological advances did grow industries and create new jobs. I have two responses. First, this article's premise is precisely that these industries will thrive; the question is whether expansion requires a proportional number of local high-income workers. Massachusetts' share of R&D output rose from 15.7% to 17% while employment fell 3.1%. IAB projects 11% growth in digital video ad spending even as the share of creative involving generative AI climbs rapidly. The evidence so far points to output and headcount decoupling. Second, even if new jobs appear, they need not appear in the same city or at the same income tier — and home prices respond to local marginal buyers, not national job totals.
Objection two: these cities are severely supply-constrained and backstopped by the wealthy, so prices cannot fall
Supply constraints do soften the shock, which is why the nine-city map explicitly separates New York, Boston, and the Bay Area from Orlando and Las Vegas. But supply only sets the magnitude; it does not change the direction. Seattle is also a high-income tech city, and after tech jobs contracted it fell roughly 10% this year. As for the wealthy backstop, Moody's Analytics data do show spending increasingly concentrated in the top 10% of households. But a city's transaction volume is driven mainly by households earning $200,000 to $300,000. The wealthy can hold up the very top of the luxury market; they cannot replace the entire marginal-buyer pool.
 Supply limits and wealthy buyers change the pace, not the direction
Objection three: Bay Area prices did not fall this year, so the call has already been proven wrong
Timing is not direction. In 2024 I made the same call for Seattle and the Bay Area. Seattle played out first; the Bay Area has not yet, because VC money reabsorbed engineers released by big tech into startups. That is a cushion contingent on the funding environment, not a reversal in fundamentals. My call comes with an explicit time window and magnitude — at least 15% over the next three years — which makes it testable. If the Bay Area sees no such correction in three years, readers should lower their confidence in this framework accordingly.
Framework Summary: Three Questions to Tell Which Side of AI a City Is On
The method in this article boils down to three core questions you can apply to any city:
- What are the city's three most important industries? Focus on anchor industries that concentrate jobs paying $200,000 to $300,000 a year.
- Ten years from now, how many local workers will these industries need for every $1 billion of output? Do not ask whether the industry will thrive; ask whether output and headcount are decoupling.
- Will those workers' incomes still be able to buy local homes? This question connects the job shock to the marginal buyer.
Then apply four adjustments:
- Classify the shock type: "boom with fewer people" (pharma, creative and advertising), "shrinking demand" (education, tourism), or "flattening pyramid" (judgment economy, tech). Each unfolds at a different speed and with different visibility.
- Look for early signals: divergence between local industry employment and output share, contraction in entry-level white-collar jobs, and weakening occupancy and revenue per available room in tourism metros.
- Layer in supply and other variables: new-supply elasticity, price-to-income ratios, migration, and interest rates determine whether the shock is amplified or absorbed.
- Net out beneficiary industries: for multi-anchor cities, account for the industries that gain from AI to arrive at the net effect.
 Three questions and four adjustments to judge any city's housing outlook
Over the next two months, I will apply this framework to ten major U.S. metros one by one — Seattle, San Francisco, Los Angeles, San Diego, Phoenix, Dallas, Austin, New York, Boston, and Washington D.C. — to measure how many high-income jobs in each are exposed to AI and how many will grow because of it, and ultimately to draw a real estate map of American cities in the AI era.
Evaluating a city's real estate is no longer about how many good jobs it has today, but about how many local people those good jobs will still need after AI.