"Don't time the market. Any time is a fine time to buy a home, just hold for the long run." This line is everywhere in real estate, and many agents reach for it when they want a client to sign. My view may not win me friends in the industry: for real estate investors, this is a false premise. It lifts a lesson from index-fund investing and applies it unchanged to an asset that works very differently. A family that takes it at face value may end up paying the most expensive lesson of their lives.
First, the boundary. When I say timing matters, I do not mean predicting the exact day prices bottom out. Nobody can do that. My claim is narrower: you don't need to know where the bottom is, but you do need to know roughly where you are in the cycle. Being unable to predict the bottom and being unable to read the cycle are two very different things.
 Not seeing the valley floor doesn't stop you from knowing you're heading downhill
This article makes no slogans and no forecast for next year's prices. It builds the case on four fronts. First, asset type: why real estate cannot be compared to a broad market index. Second, market cycles: why the housing cycle can be read even though the bottom can't be called. Third, valuation and leverage: why even a great home can be a bad investment at the wrong price. Fourth, purpose: why investment properties and primary residences need different standards. I then respond to the most common objections and close with a checklist readers can apply on their own.
Lessons from Las Vegas: Same House, Only the Purchase Date Differs
Claim: The same kind of asset bought at different points in the cycle can produce wildly different outcomes. "It eventually came back" tells you whether you broke even. It does not tell you whether you bought right.
Mechanism: At the top of a cycle, market prices already include too much optimism about the future. Buyers pay for the home's real value plus an emotional premium built on the belief that prices will keep rising. When sentiment turns, that premium disappears first, and a leveraged buyer absorbs the entire loss.
Evidence: In 2006, at the height of the U.S. housing frenzy, people buying in Las Vegas heard almost exactly what buyers hear today: the population is still growing, land keeps getting more expensive, prices always rise over time, and if you hold long enough short-term swings don't matter. Then the bubble burst. According to historical price data compiled by Wei Li's team, Las Vegas home prices fell roughly 62% from the 2006 peak to the post-financial-crisis low. In theory, a $1 million home was worth about $380,000.
Picture two buyers. One bought in Las Vegas in 2006. The other waited until after the housing crisis. They may have bought in the same city and the same neighborhood, possibly very similar houses. The one big difference was when they bought.
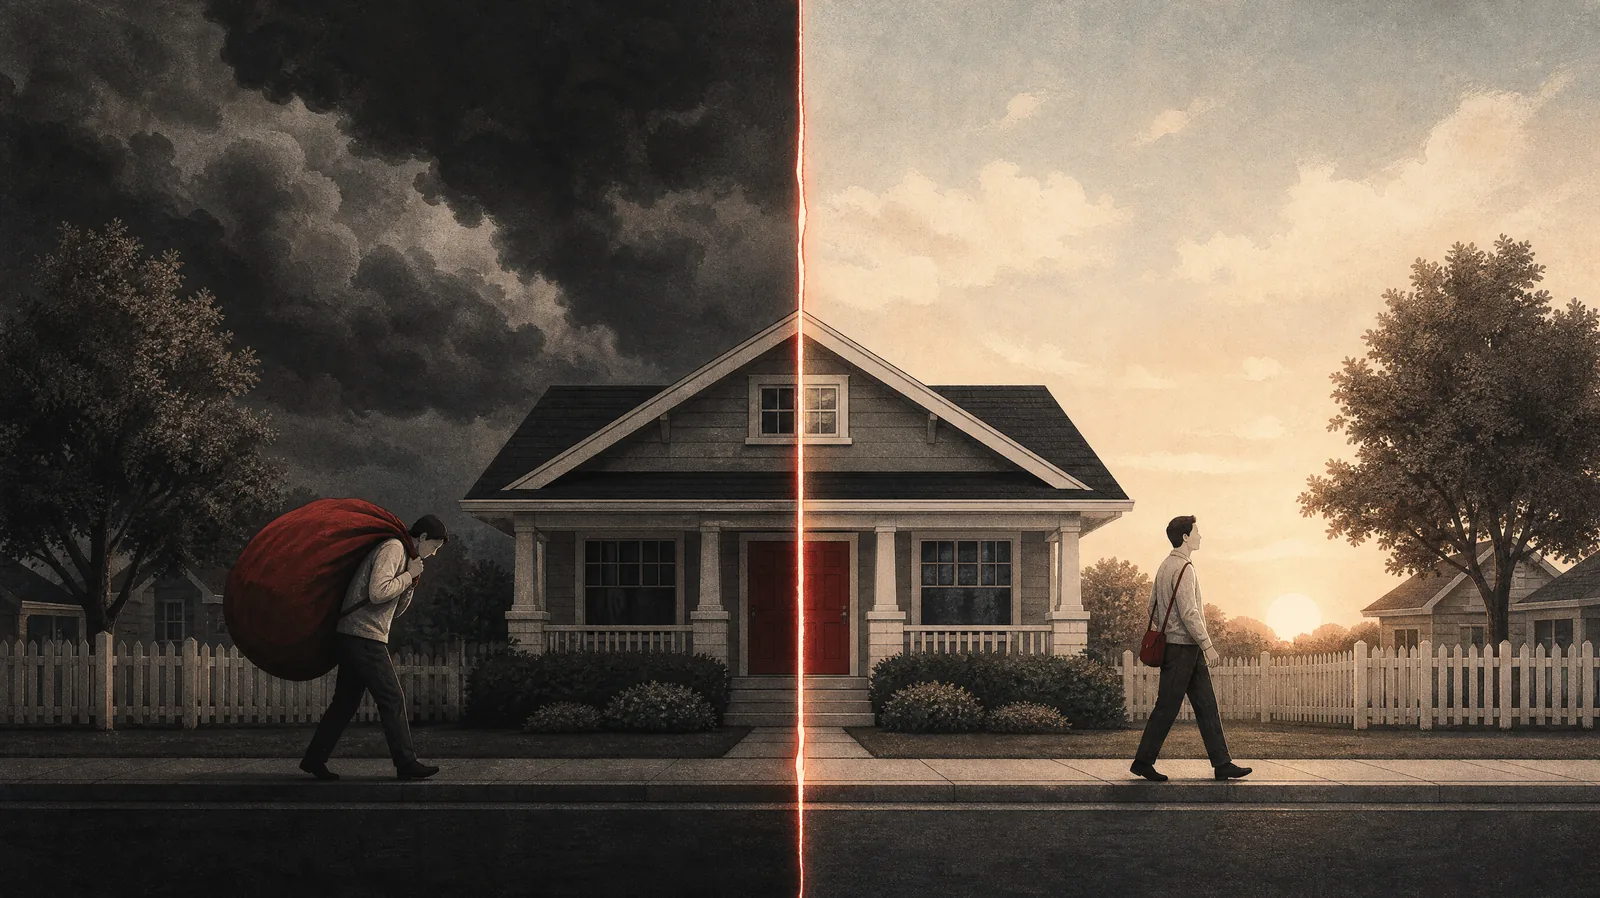 Same city, same neighborhood, same house—only the timing made their fates diverge
What this means: People often push back: "But if you bought in 2006 and held on, didn't it eventually recover?" Yes. But breaking even and buying right are different questions. Through all the years it took to climb back from the peak, the owner kept paying interest, property taxes, insurance, and maintenance, money that could have worked elsewhere. The bigger practical risk is that many owners never made it to the recovery. Once their income stopped, they were forced to sell at the worst possible price.
Getting your money back eventually doesn't mean you bought right. The question isn't "Will I break even in twenty years?" It's "Why should I put this money to work today, at this price?"
So whether timing matters in real estate is not really in dispute. The real question is whether we can read the big housing cycle. My answer is yes. The next four sections explain why.
Asset Type: Buying a Home Is Not Buying an Index
Why "don't time the market" works for index investing
The stock-market maxim "don't time the market" fits index investing like the S&P 500 best. You own hundreds of companies. If tech struggles, you still have healthcare, financials, energy, and consumer names. The index diversifies your risk for you, so a valuation mistake in any one sector or company gets diluted by the portfolio. In that setting, timing adds little at the margin, and buy-and-hold makes sense.
Real estate risk is nested, layer by layer
Buying a home is completely different. You are not buying a real estate fund spread across dozens of U.S. cities. You are buying one city, one neighborhood, one school district, one property type, and one price band, and in the end one specific house.
Those layers don't move together. U.S. prices rising doesn't mean Seattle is rising. Seattle rising doesn't mean Bellevue is rising. And Bellevue rising doesn't mean $3 million homes in Bellevue are rising. Each market has its own buyers, with different income sources, different sensitivity to interest rates, and different expectations. The national average price is a statistic. Nobody can actually buy it.
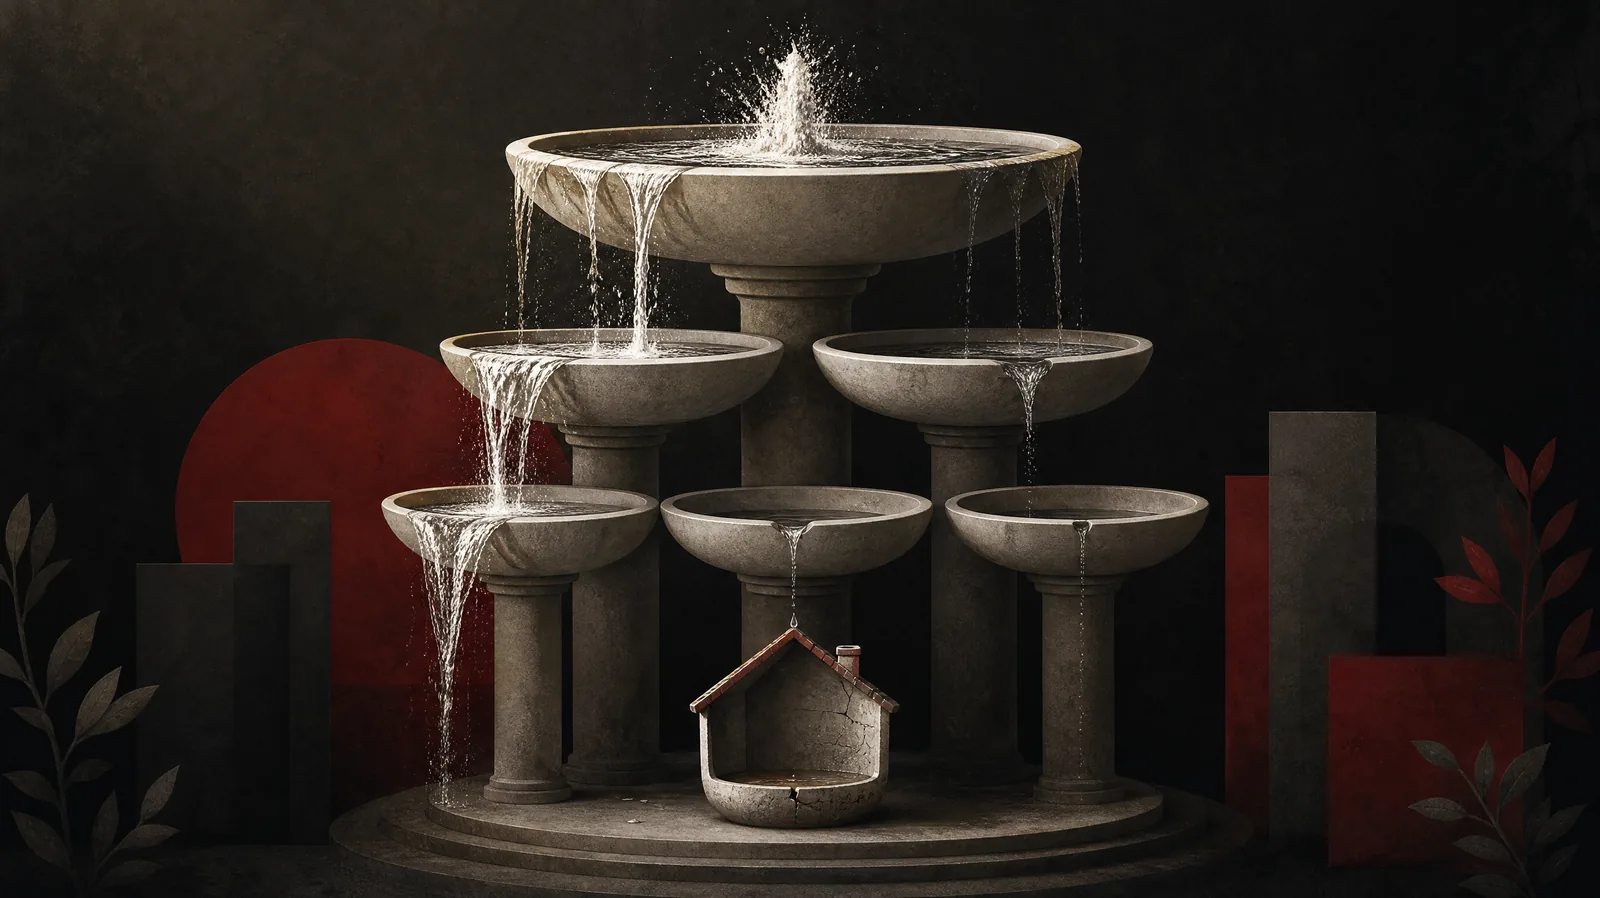 A national rise doesn't mean your city rises, let alone your specific house
As an investment, buying a home looks less like owning an index fund and more like putting hundreds of thousands, or millions, of dollars into a single stock, with leverage.
The right question: Who will buy my home five years from now?
So the right question for a real estate investor has never been "Will U.S. home prices rise over the long run?" It is "Who will buy my home five years from now?" That breaks down into three questions you can actually check:
- Are those future buyers' incomes rising or falling?
- Is the number of high-paying jobs in this city growing or shrinking?
- Is the pool of buyers in this price band getting bigger or smaller?
What this means: You are not just buying a location. You are buying the economy behind that location. I spent 11 years at Microsoft and have since worked with more than 200 Chinese American families in Seattle. The pattern I see most often is people studying the house in fine detail and doing almost no homework on who will buy it from them later. Yet that second question is what determines the exit price.
 Your exit price depends on who will take the house from you five years from now
Cycle Signals: Volume Drops First, Not Prices
Claim: The housing cycle can be read precisely because prices adjust so slowly. Sales and inventory send signals before prices do.
Sellers anchor to old prices
Suppose your neighbor sold their house last year for $2 million. This year the market softens, and buyers will only offer $1.8 million. Would you immediately accept that your house is worth $1.8 million? Most sellers won't. The usual pattern is to list at $2 million and get no takers, cut to $1.95 million and still get nothing, then pull the listing and relist a few months later.
Here is the mechanism: buyers no longer accept yesterday's prices, but sellers are still living in them. A gap opens between what each side will accept, so transactions disappear first. Homes get harder to sell, days on market stretch out, inventory piles up, and only after time wears down sellers' expectations do prices adjust visibly.
The order in which indicators move
Following that mechanism, when a market turns, the indicators tend to move in roughly this order:
- Sales volume falls, the first place the price gap shows up;
- Pending sales decline, as fewer deals reach contract;
- Days on market lengthen;
- Inventory builds;
- The share of listings with price cuts rises;
- Only then do sale prices adjust meaningfully.
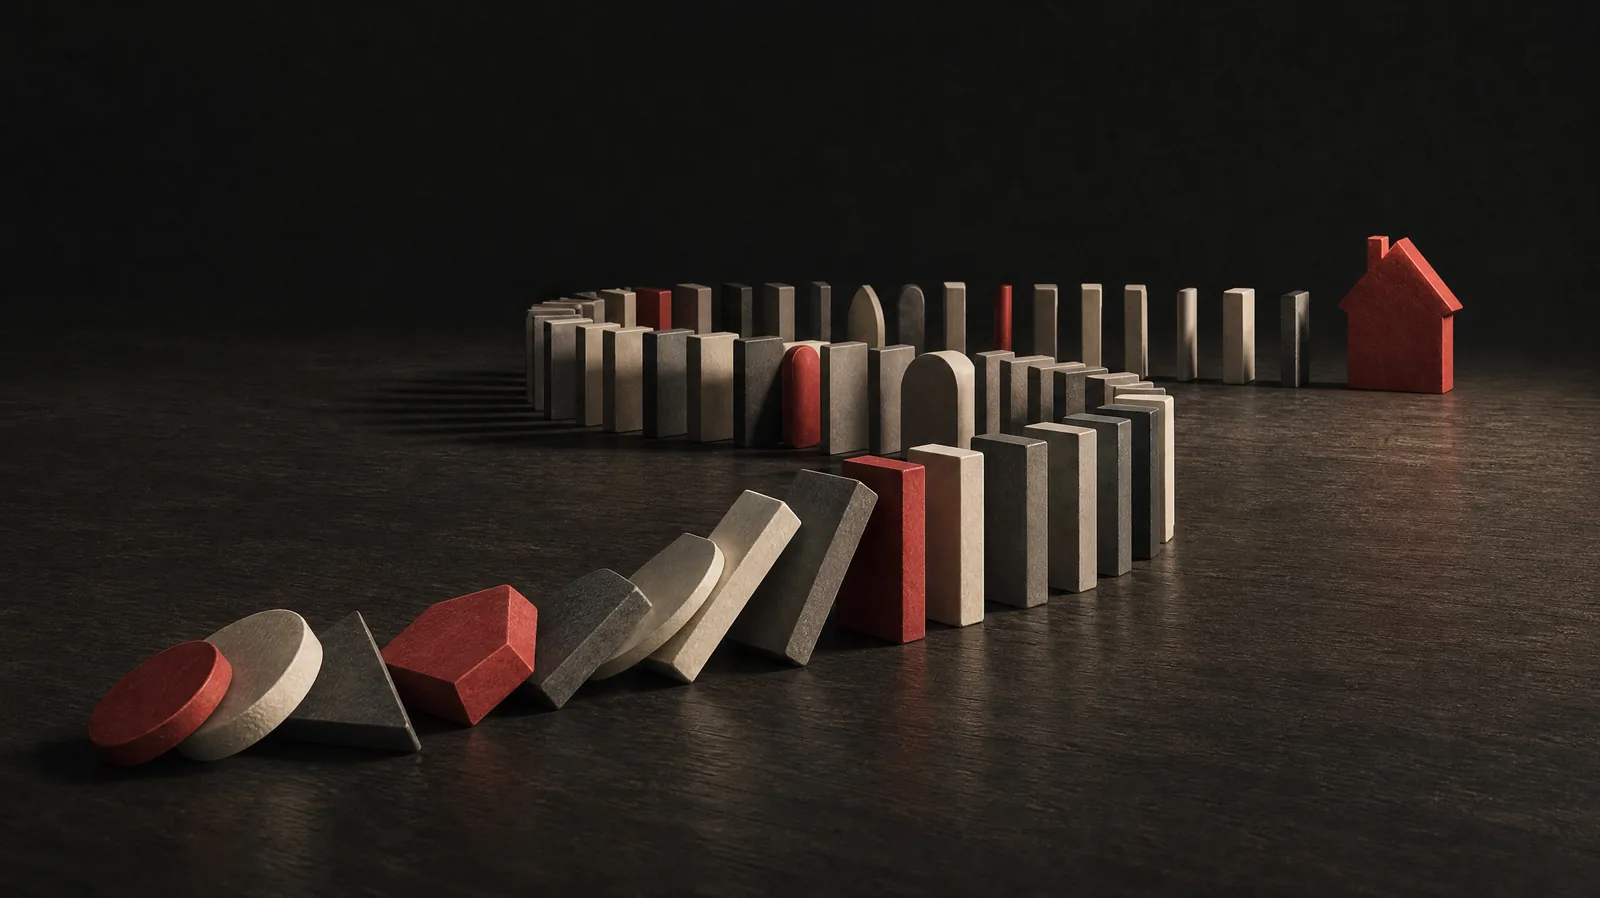 Sales and inventory fall first; price is always the last domino
For more on how rising inventory shifts bargaining power between buyers and sellers, see my analysis of Seattle's inventory surge and the shift to a buyer's market.
Why this makes the cycle readable
What this means: Price is a lagging indicator. If you only watch prices, you are always seeing the market as it was several stages ago. This is exactly why "you can't call the bottom" and "you can't read the cycle" are different claims. The bottom is only known in hindsight, but the first five indicators can be observed before prices move in a meaningful way.
Most people watch prices. People who actually read the cycle watch sales and inventory first. By the time prices tell you the market has changed, it usually changed a while ago.
Valuation and Leverage: A Good Home Is Not Necessarily a Good Investment
A good house and a good investment are different things
Stock investors talk about valuation constantly. Even a great company isn't worth buying at any price. In real estate, though, valuation talk often vanishes and three slogans take over: good schools, good location, prices always go up.
Mechanism: If the only reason you're buying is "this city has gone up for the past ten years," you're no longer investing in the home's fundamentals. You're betting that someone will always be willing to pay more than you did. That works while the assumption holds. When it stops holding, the assets with the richest valuations have the most room to fall.
Evidence: Seattle's decline this year is a direct counterexample. According to Wei Li's team's tracking of Seattle-area market data, Bellevue, the favorite city of Chinese American buyers, fell 10% from January to July this year, while Seattle City fell only 3%. The best neighborhoods and the best homes fell fastest. My reading is that the segments people chased hardest on the way up also had the most stretched valuations, and their buyer pool was more concentrated. When those buyers' income outlook weakens, demand contracts all at once.
 The most coveted, highest-valued areas often fall hardest in a downturn
What this means: "Prime locations always hold their value" does not survive a downturn. Prices are driven by where the purchase price sits relative to fundamentals and by the makeup of the buyer pool, not by a school or location label. I make the full case in The Myth That Prime Locations Hold Their Value.
Leverage turns price risk into principal risk
Real estate has one more feature index investors rarely face: leverage.
Run a simple example. You buy a $2 million home with 20% down, or $400,000. If the price drops 10%, or $200,000, half your original down payment is gone. And that's before interest, property taxes, insurance, maintenance, and transaction costs.
Many people think they've bought "a house that might drop 10%." What they've actually bought is a leveraged asset where a 10% price decline can wipe out half the down payment. Leverage doesn't make prices swing more, but it multiplies what those swings do to your principal.
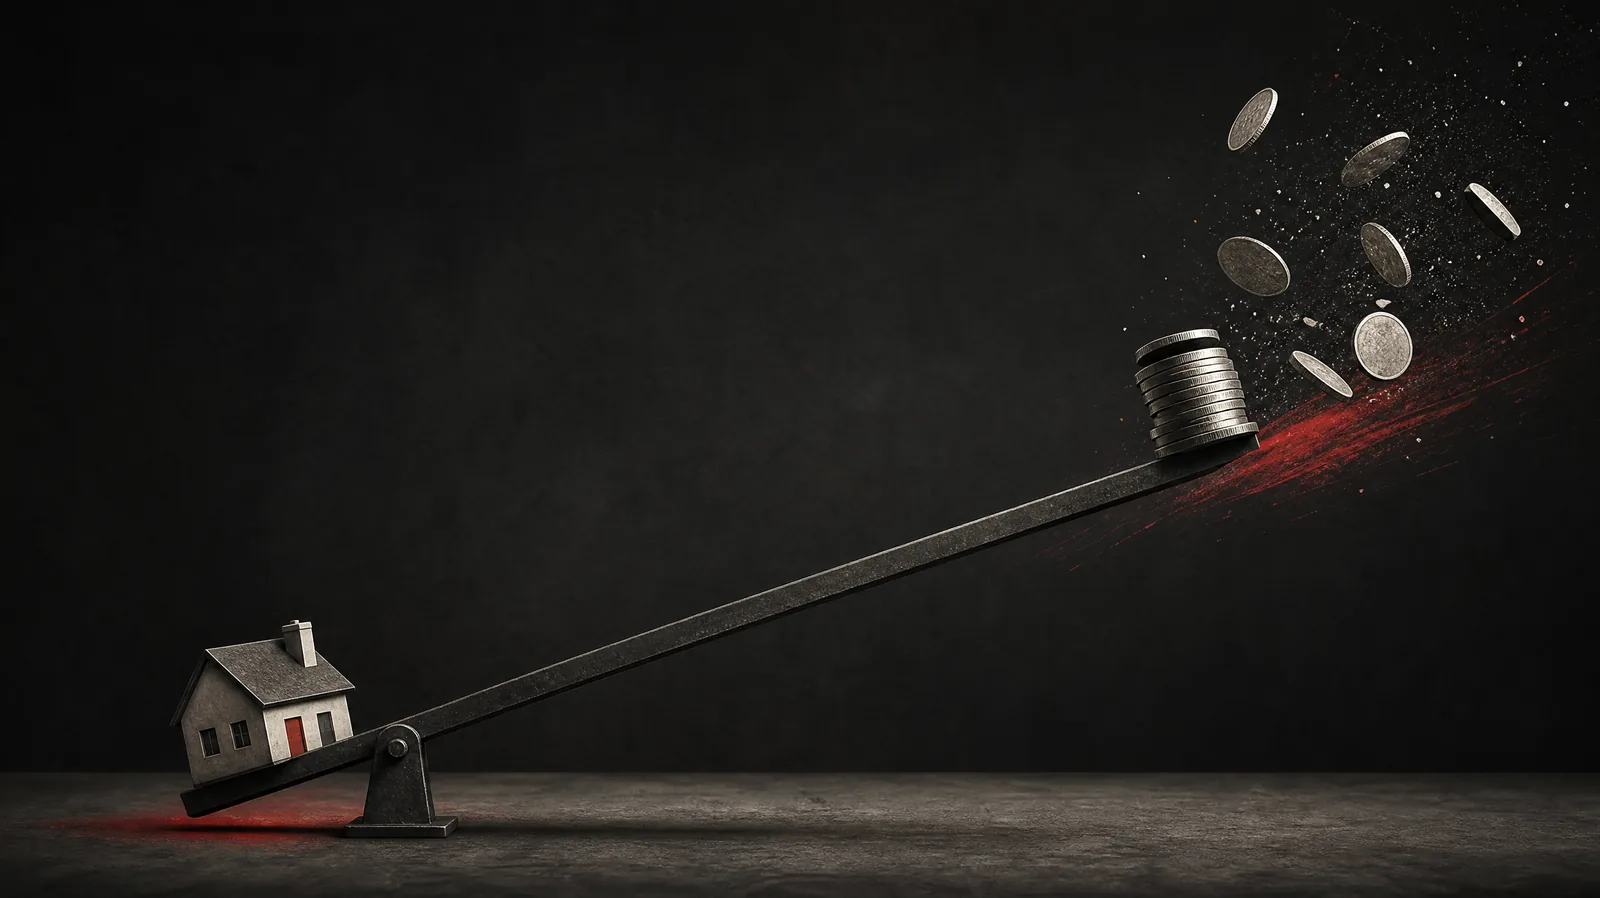 Leverage doesn't change price swings, but it multiplies their blow to your capital
On a home bought with 20% down, a 10% price decline can wipe out half the down payment. Saying entry price doesn't matter for an asset like that simply doesn't hold up.
In fact, entry price matters more in real estate than in a broad market index. The position is concentrated, with no diversification. It's leveraged, which magnifies losses. And because transaction costs are high and liquidity is low, fixing a bad purchase is expensive.
Purpose: Two Standards for Investment Properties and Primary Homes
The argument so far is mostly about investing. When the purpose of the purchase differs, the standard should too.
Investment properties: watch two cycles
If you're buying an investment property, focus on two things: the economic cycle and the real estate cycle.
- Economic cycle: employment, interest rates, and whether the region's main industries are expanding or contracting.
- Real estate cycle: inventory, sales volume, days on market, rents, and valuation.
When both cycles point up, investors get the strongest tailwind. When both point down, no single property's strengths can offset the systemic headwind. My assessment is that both the U.S. economic cycle and the housing cycle are currently trending down. For investment-property buyers, there is no compelling reason to enter now. To apply these indicators to a specific property, see 5 Key Metrics Every Real Estate Investor Must Master.
 When both economic and housing cycles turn down, no single property's merits beat the headwind
Primary homes: four questions to answer honestly
A primary residence works differently because it also delivers value as a place to live. Before you make an offer, answer four questions honestly.
First, will you most likely live in this home for the next 5 years? If there's a good chance you'll change cities, jobs, or school districts in two or three years, short-term price swings matter a great deal to you. Buying and selling real estate is expensive, and the shorter you hold, the more your purchase price drives your result.
Second, are your job and income stable? I don't mean whether you have a job today. I mean whether your income would still be fairly secure if the economy weakens over the next year or two and companies start laying people off.
Third, if you lost your job tomorrow, do you have at least 24 months of living expenses, including the mortgage, in cash reserves? Falling prices alone won't necessarily force you to sell. What actually pushes many people to sell at the worst time is running out of cash flow. This is a point I stress repeatedly in Should You Sell Your Home After a Layoff?
 It's usually a cash-flow break, not falling prices, that forces sales at the worst time
Fourth, if you buy this home today and prices fall another 10% next year, will you regret it? If your answer is "No, I love this house, we plan to stay for years, the kids go to school here, and the mortgage is easily affordable," then you're mainly buying a place to live, and you don't need to time the bottom. If your answer is "Another 10% drop and I'd definitely feel I made a mistake," stop and think. You may call it your home, but you still see it as an investment, so it should be held to the investment standard.
The test for buying a primary home isn't "Is this the bottom?" It's "If prices fell another 10% in the short run, would I still want this home, and could I afford to keep it?"
My standard is simple: you plan to stay long-term, your income is stable, your cash reserves are sufficient, and you would still want to own the home even if prices dropped another 10% in the near term. If all of that is true, there's no reason to keep waiting for the bottom. If several of the answers are "no," then "prices always go up in the long run" shouldn't be your reason to buy today.
Counterarguments and Responses
Objection 1: "Long-term holders always recover. Las Vegas proves it."
This is the most common objection and the most reasonable one, so I'll answer it on three points.
First, it describes where prices ended up but ignores the cost of getting there. From the 2006 peak back to the original price, the owner kept paying interest, property taxes, insurance, and maintenance, while the same money invested at a different time would have produced a very different result. Second, "it came back" only applies to people who made it through the whole stretch. Those who lost their jobs or ran out of cash and had to sell near the bottom never got the recovery. Third, Las Vegas recovering doesn't mean every city and every price band recovers at the same pace. As discussed earlier, U.S. prices rising doesn't mean Seattle is rising, and Seattle rising doesn't mean a specific price band is.
So this objection shows that holding for the long run sometimes gets you back to even. It does not show that purchase timing doesn't matter.
Objection 2: "Even professionals fail at market timing, so ordinary buyers have no chance."
In the stock market this has some merit, but it blurs two different things: picking the exact entry point and knowing where you are in the cycle. In a market with daily pricing and deep liquidity, trying to buy on the exact bottom day is close to futile. I'm not recommending that.
Real estate is the opposite in important ways. First, prices adjust very slowly and volume leads price, so the leading indicators can be observed before prices move meaningfully. The information you need to read the cycle is easier to get than in stocks. Second, high transaction costs, low liquidity, and leverage make a bad purchase far more costly than a bad stock trade, so reading the cycle is well worth the effort. In stocks, the payoff from timing may not cover its cost. In real estate, skipping the cycle check can cost you half your down payment.
 Picking the exact moment is futile, but locating the cycle is homework you can do
Objection 3: "If you wait, you may miss out. Shouldn't you buy a primary home whenever you're ready?"
I've written Why "Buy Your Primary Home Whenever You're Ready" Is the Best Strategy myself, so this objection deserves a direct answer. That conclusion rests on conditions: you will truly live there, hold for the long term, have stable income, and have enough reserves. The four questions in the previous section turn those conditions into a test you can check. Families who pass it really don't need to wait for the bottom, and that does not conflict with anything in this article.
What this article argues against is a different situation: using "you can buy a primary home anytime" to justify what is really an investment decision, or talking yourself into a purchase with "prices always go up" when the conditions aren't met. Missing a window usually costs you an opportunity. Buying with leverage under the wrong conditions can cost you your principal.
Not being able to predict the bottom doesn't mean you can't tell expensive from cheap. Not being able to buy at the exact low doesn't mean you can't read supply, demand, and the cycle.
Framework Summary: A Cycle-Positioning Checklist You Can Use
Here is the article's method distilled into eight steps. It won't predict next year's prices. It helps you answer one question: Given my purpose and finances, is the risk of buying at this time and this price within what I can handle?
- Confirm your purpose. Is this an investment property or a primary home? Use the fourth question as the test. If another 10% drop would definitely leave you regretting the purchase, go through every step using the investment standard.
- Locate the economic cycle. Is local employment growing or shrinking? What is the rate environment? Are the region's main industries expanding or contracting?
- Locate the real estate cycle. Check, in order, sales volume, pending sales, days on market, inventory, and the share of price cuts, and look at prices last. For investment properties, add rents and valuation.
- Answer "Who buys from me in five years?" Are buyers in your target price band seeing their incomes rise or fall? Are high-paying jobs in this city growing or shrinking? Is the pool of buyers in this price band getting bigger or smaller?
- Run a valuation check. If "it's gone up for ten years" is your only reason to buy, you're betting that someone will pay more later, not on fundamentals.
- Stress-test your leverage. Using your own down payment percentage, how much principal would a 10% price decline cost you? Then add interest, property taxes, insurance, maintenance, and transaction costs.
- Test your staying power. Are you likely to stay put for the next 5 years? Would your income remain fairly secure in a downturn? Do you have at least 24 months of reserves, mortgage included?
- Decide. For investment properties, stay out while both cycles are trending down, and reconsider once risk starts to clear, valuations become more reasonable, and supply and demand turn in your favor. For a primary home, if you pass every part of step 7 and can calmly accept another 10% drop, there's no need to wait for the bottom.
Mature real estate investing isn't about buying at the exact bottom. It's about getting in as risk starts to clear, valuations become more reasonable, and supply and demand begin to move in your favor.
Conclusion: Not Being Able to Call the Bottom Is No Excuse to Buy Blind
"Don't time the market" is sound discipline for index investing. Applied to real estate, it becomes a false premise. Real estate is concentrated, leveraged, and illiquid. Your purchase price determines how much risk you carry, and your position in the cycle determines whether you hold with the wind at your back or in your face.
Two lines to leave you with. Getting your money back eventually doesn't mean you bought right. Don't expect to buy at the exact bottom, but always know where you are in the cycle. Being unable to call the bottom has never meant you should buy with your eyes closed.