From 2019 to 2024, employment in the Greater Boston metro area fell from 2.722 million jobs to 2.708 million, a five-year decline of 0.5% (U.S. Bureau of Labor Statistics, QCEW, 2024). Over the same period, Boston's typical home value rose 47.6%, reaching a record $725,639 in September 2026 (Zillow ZHVI, September 2026). Dallas, the subject of my previous report, did the opposite: employment grew 10.3% in five years while prices rose only 37.5%. A city that is shedding jobs sets price records while the fastest-growing job market in the country underperforms the nation—this is not a coincidence. It is a key to understanding how American home prices actually work.
 Jobs shrink while prices climb: Dallas and Boston sit on two opposite kinds of balance.
My core judgment splits into two time horizons. Over two years, Boston's prices are determined by supply: new homes cannot be built, and owners locked into roughly 3% mortgages will not sell, so even if research funding and life sciences keep contracting, overall prices are unlikely to fall much. The most probable outcome is modest gains on thin volume. Over ten years, Boston's prices are determined by demand: what carries a $730,000 median home today is roughly 320,000 jobs paying over $150,000 a year, 89% of which are white-collar roles that earn their money through analysis and judgment—precisely the jobs most exposed to the second wave of AI. Scarce supply does not protect prices; it makes them more sensitive to demand. It is an amplifier on the way up and an amplifier on the way down. Boston demonstrated this once already after 1988.
This is the second installment of my ten-city deep-dive series. The article has eight sections: why the demand side is weak; why supply can turn weak demand into record prices; the geographic divergence inside Boston; the two-year and ten-year risks, separately; concrete guidance for buyers, sellers, and investors; responses to the most likely objections; and a checklist that applies the method to any city. The full 48-page research report, Supply Constraints and the Affordability Boundary, is available free in the site's Housing Map · City Reports, so I won't reproduce every chart here.
Three Weaknesses on the Demand Side: Flat Jobs, Departing High Earners, Priced-Out Median Households
Boston's demand-side problem is not recession but stagnation—zero job growth, a persistent net outflow of high-income households, and a local median family that can no longer afford the median home.
The intuitive view of Boston is that Harvard, MIT, and Massachusetts General Hospital are all here, the smartest people in the world cluster here, so how could the economy be weak? The employment data answer: it is not weak, it is stuck. BLS QCEW shows metro employment down 0.5% from 2019 to 2024. By industry, comparing August 2026 to the end of 2019, information employment is down 14.8%, finance down 6.2%, and professional, scientific, and technical services—which include biotech R&D—down 0.9%. The only sector still growing is health care, up 3.4% (BLS CES, August 2026). In other words, nearly all of Boston's net job creation in recent years has come from hospitals and nursing, while every traditionally high-paying industry has shrunk.
 Elite universities and hospitals remain, but employment has stopped growing: a still pool behind a grand facade.
Boston does have one thing Dallas cannot match: the existing wage base. Average annual pay in Boston was $103,714 in 2024, up 26.3% in five years and 37% above the national average (BLS QCEW, 2024). Boston has roughly 320,000 jobs paying over $150,000, compared with 194,000 in Dallas, even though Boston's total employment is only about two-thirds of Dallas's (BLS OEWS). This explains why prices have not fallen despite flat employment: the high-income households already here have the cash flow and assets to carry today's prices. Mechanically, short-run price support comes from the purchasing capacity of incumbent owners, not from the count of new jobs.
The problem is that new buyers are draining away, and the ones leaving are exactly the ones with the most purchasing power. Census Bureau estimates show Greater Boston's population grew by only 113,000 from 2020 to 2025, entirely from international migration and natural increase; interstate migration has been negative every year, with a net domestic outflow of 29,132 people in 2025 alone, barely offset by a net international inflow of 30,913 the same year (Census Population Estimates, 2025). More telling is the income profile of movers: IRS migration data show that households moving into Boston from other states in 2022–2023 earned an average of $101,000, while those leaving earned $131,000—and the pattern has held every year for four years (IRS SOI, 2022–2023). Those leaving are the upper-middle-income families most likely to buy; those arriving are students, researchers, and early-career workers who rent first.
Can the families who remain afford to buy? By Zillow's method—20% down, payment capped at 30% of income—buying a median-priced Boston home requires household income of $195,229, up from $108,224 at the end of 2019; the metro's median household income is only $117,825 (Zillow; Census ACS). The monthly payment makes this concrete. At the end of 2019, the median home cost $498,000 at a 3.72% rate, for principal and interest of about $1,838 a month. Today the home costs $725,639 at a 30-year fixed rate of 7.32% (Freddie Mac PMMS, October 22, 2026), for principal and interest of about $4,031. Prices rose 47%; the payment multiplied by 2.2. Add property tax at Boston's residential rate of $12.40 per $1,000 (Boston.gov) and insurance, and the all-in monthly cost runs $4,800 to $5,060—after a down payment of roughly $150,000.
 The median household's income ladder no longer reaches the median home price, though it did a few years ago.
| Metric | End of 2019 | Latest 2026 | Source |
|---|---|---|---|
| Metro typical home value | $498,000 | $725,639 (+47.6%) | Zillow ZHVI, Sept 2026 |
| 30-year fixed rate | 3.72% | 7.32% | Freddie Mac PMMS, Oct 2026 |
| Monthly principal + interest | ~$1,838 | ~$4,031 | Calculated from the above |
| Income needed to buy | $108,224 | $195,229 | Zillow |
| Median household income | — | $117,825 | Census ACS |
Put the three together: jobs are not growing, high earners are leaving, median families cannot afford to buy. By conventional logic, prices should fall. They have not—and the answer is supply.
The Supply Constraint: Why a City With Flat Demand Still Sets Price Records
What makes Boston unusual is not strong demand but extraordinarily thin supply: new homes cannot be built and existing homes are not being listed, so prices react sharply to even small shifts in demand.
In the Dallas report I introduced housing-supply elasticity—simply, how easily a city can add homes. Wharton's Albert Saiz measured 95 U.S. metros; the lower the number, the harder it is to build (Saiz, QJE, 2010). Dallas scores 2.18 and Fort Worth 2.80. Boston scores 0.86, the 15th most constrained of the 95. The mechanism has two layers. Geographically, the Atlantic, the harbor, the Charles River, and extensive wetlands fragment the buildable land. Institutionally, Massachusetts has 351 municipalities, each controlling its own land-use approvals; many suburbs permit only single-family homes, and a multifamily project can languish in review for years.
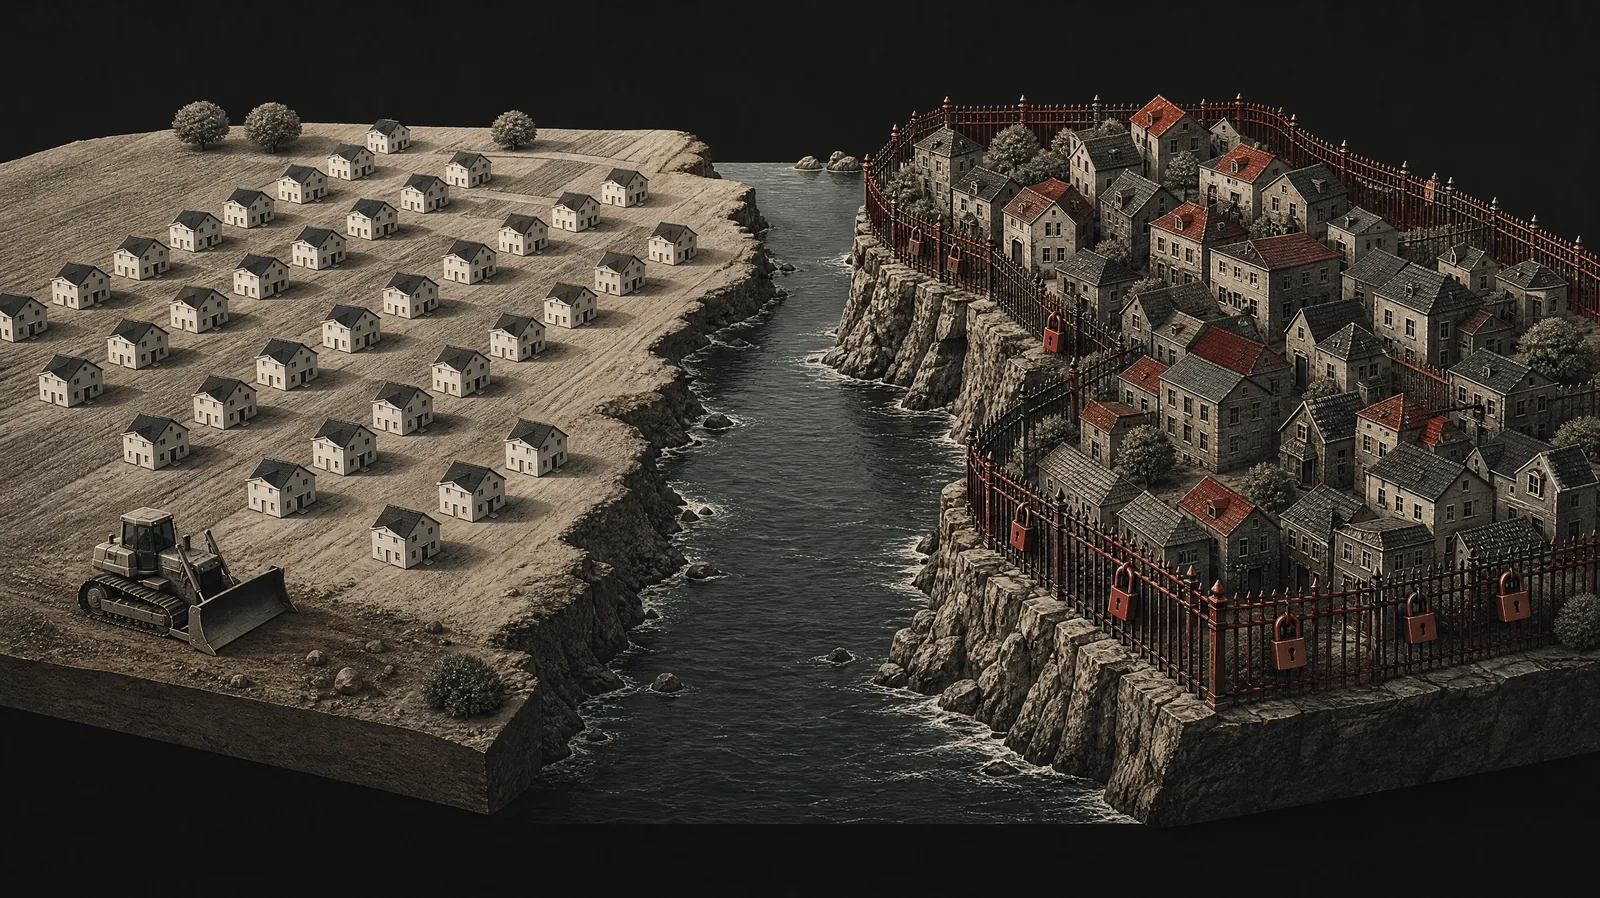 The gap in supply elasticity: open farmland on one side, a rocky shore fenced off by geography and rules on the other.
The permit data show the result. From 2020 to 2025, the Boston metro approved 76,574 housing units; Dallas approved 423,440 (Census BPS, 2025). In 2025 Boston issued only 10,072 permits on a seven-county basis, the lowest in six years; on the Census/FRED metro monthly basis, just 9,295, the lowest since 2015, down from a 2021 peak of 17,216. Per capita, Boston permits 2.0 units per 1,000 residents; Dallas permits 7.8. The metro has about 1.97 million households (Census ACS) and adds roughly 10,000 homes a year—not enough even to cover normal household formation from young adults leaving home and seniors living alone, let alone net new demand.
New homes are not being built, and existing homes are not coming to market. Many owners bought in 2020–2022 at roughly 3%; selling and buying again means taking on a loan above 7%, so they stay put. Realtor.com data show new listings in Boston over the past 12 months at only 79% of pre-pandemic levels and active inventory at about 80%, with the result that the median listing sells in 43 days, faster than the pre-pandemic 48 (Realtor.com, 2026). Note what this combination means: homes sell quickly not because buyers are plentiful but because there is less to choose from.
A regression across 73 U.S. metros makes the amplification explicit: in Dallas, a 1% increase in employment barely moves prices; in Boston, a 1% increase in employment lifts prices by roughly 2.3% (my regression on BLS, Zillow, and Saiz data; appendix to the first report). This is why Boston's prices rose 47% while employment stagnated—wages rose 26%, new supply was close to zero, and incumbent owners did not sell, so every increment of purchasing power converted directly into price.
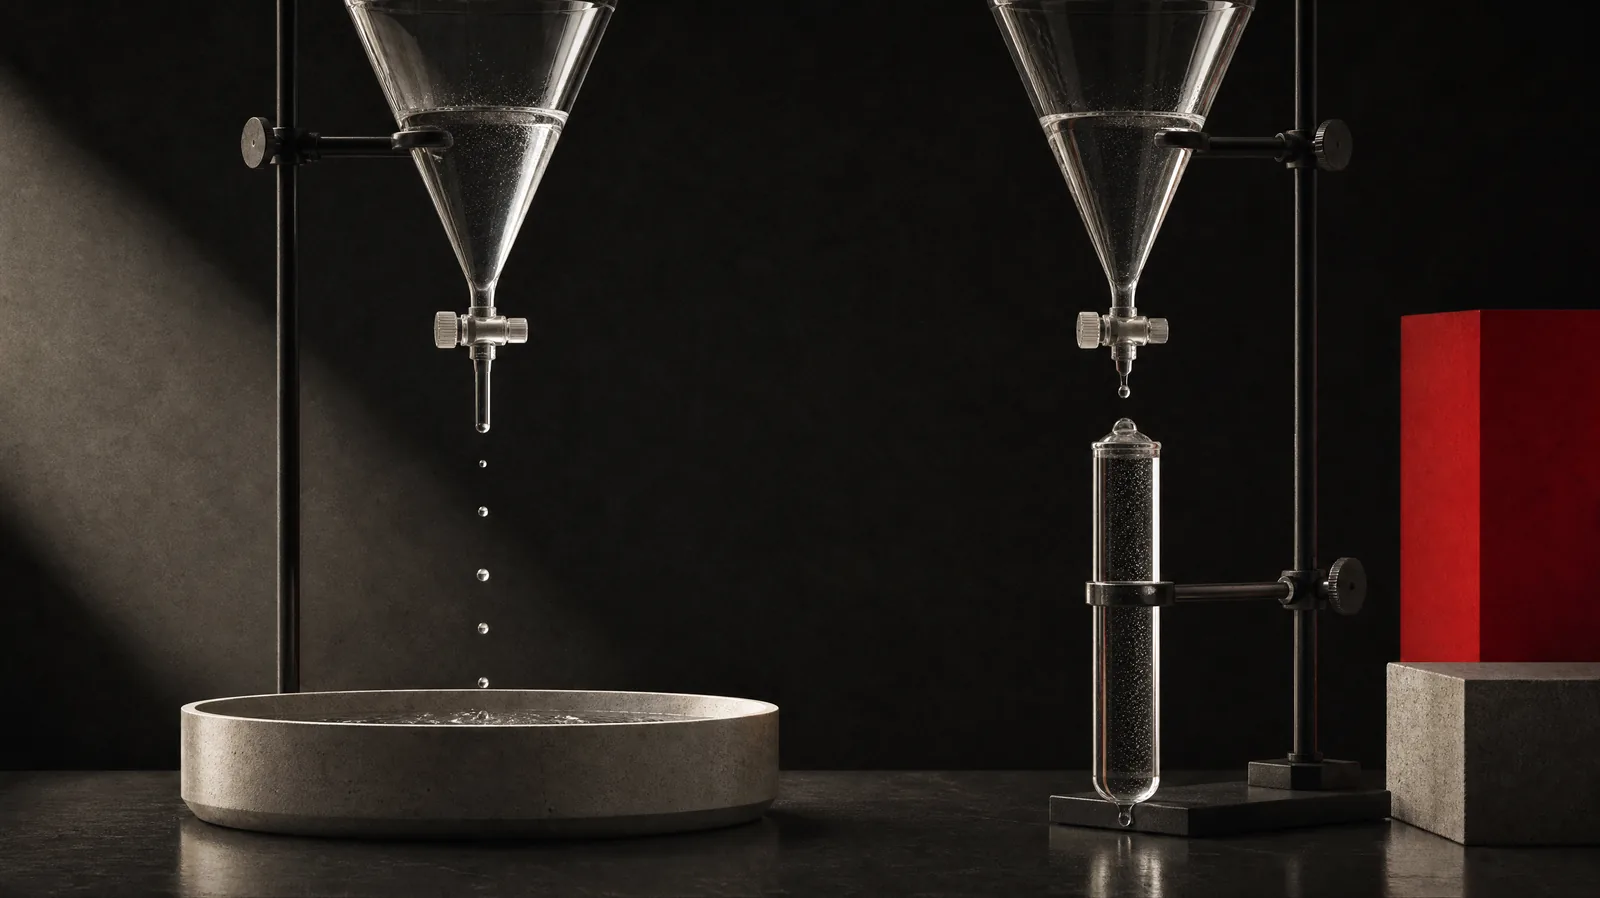 The same drop of demand barely registers in a wide basin but becomes price in a narrow tube.
| Metric | Boston | Dallas–Fort Worth | Source |
|---|---|---|---|
| Housing-supply elasticity | 0.86 (15th most constrained of 95) | 2.18 / Fort Worth 2.80 | Saiz, QJE, 2010 |
| Permits, 2020–2025 | 76,574 | 423,440 | Census BPS |
| Permits per 1,000 residents, 2025 | 2.0 | 7.8 | Census BPS |
| Employment change, 2019–2024 | −0.5% | +10.3% | BLS QCEW |
| Price change since end of 2019 | +47.6% | +37.5% | Zillow ZHVI, Sept 2026 |
| Price response to +1% employment | ~+2.3% | ~0 | 73-metro regression |
Geographic Divergence: The Core Gained the Least on Price and the Most on Rent
Boston's divergence is not by price tier but by geography: the core, home to the best universities and hospitals, has seen the smallest price gains and rent increases roughly double those gains—demand has not disappeared, it has shifted from buying to renting.
From the end of 2019 to September 2026, Boston's outer ring and gateway cities posted striking gains: Lowell up 59.7%, Plymouth up 64.9%, Wellesley up 61.3%. The core is a different picture: Boston City up only 15.5%, Cambridge 14.2%, Somerville 17.0%, and Brookline just 6.9%—down 4.8% over the past three years (Zillow ZHVI, September 2026). Condos are starker still: metro prices rose 47.6%, condos only 31.2%, and only 0.9% in the past year. Harvard, MIT, and Mass General are all in the core. Why did the core gain the least?
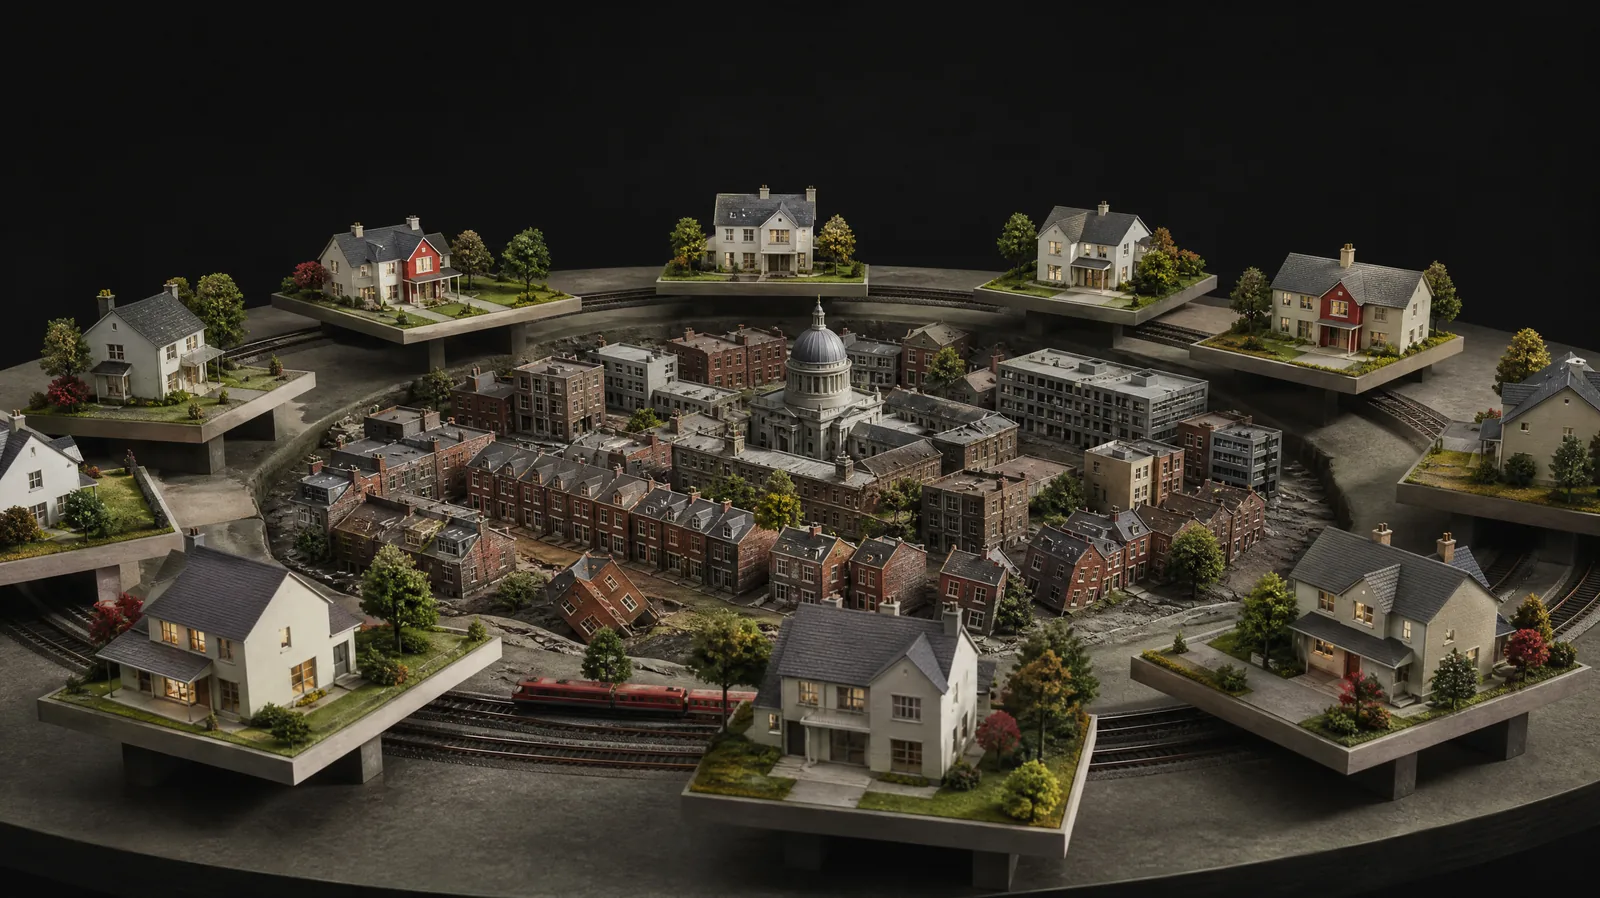 The weakest gains are in the prime core; the outer single-family ring is lifted highest.
I see three mechanisms working together. First, the core is dominated by condos and older housing, and post-pandemic buyers prefer single-family homes with yards, so demand migrated structurally to the suburbs. Second, core buyers come disproportionately from life sciences, tech, and academia—exactly the groups that have contracted most since 2023 (BLS CES: information −14.8%, professional and technical services −0.9%). Third, the core was already the most expensive, so affordability broke there first: Zillow's buying threshold is $195,000 of household income, and the core is full of well-paid professionals who nonetheless fall well short. These three points mirror the Eastside Seattle logic I laid out in Does a Prime Location Really Hold Value?: a location premium depends on the income structure of a specific buyer pool, not on the location itself.
None of this means people no longer want to live in the core. Rents prove otherwise. Brookline prices rose 6.9% while rents rose 31.0%; Cambridge prices 14.2%, rents 24.5%; Boston City prices 15.5%, rents 29.2%; Somerville prices 17.0%, rents 33.0% (Zillow ZORI, September 2026). Core rents rose roughly twice as fast as core prices. More people want to live there; more of them are choosing to rent rather than buy. Boston's colleges enroll close to 160,000 students (BPDA, fall 2022; Northeastern about 40,000, Boston University about 32,000), and with postdocs and residents added, nearly all of them rent. 39.0% of metro households rent, and 51.5% of renters spend more than 30% of income on housing (Census ACS).
| Town | Price change (end 2019–Sept 2026) | Rent change (same period) | Assessment |
|---|---|---|---|
| Brookline | +6.9% (−4.8% over 3 years) | +31.0% | Weakest buyer demand, strongest renter demand |
| Cambridge | +14.2% | +24.5% | Direct hit from life-sciences contraction |
| Boston City | +15.5% | +29.2% | Dragged by condos |
| Somerville | +17.0% | +33.0% | Beneficiary of spillover rental demand |
| Lowell | +59.7% | — | Where priced-out buyers went |
| Plymouth | +64.9% | — | Single-family preference plus low base |
| Wellesley | +61.3% | — | High-income chase for detached homes |
The household arithmetic makes it concrete. A couple earning $150,000 sounds comfortable, but that is only 76.8% of the buying threshold; by the same rules they can afford a home of about $564,000, well short of the $726,000 median (combined calculation from BPDA, Census ACS, and Zillow). Owning a median home costs $4,800 to $5,060 a month; renting a single-family home costs roughly $3,500 to $3,650 (Zillow ZORI, September 2026). The gap is $1,150 to $1,560 a month, with no $150,000 down payment required. What has happened over the past several years is simple: buyers priced out of the core went to the suburbs and gateway cities; people who must stay in the core increasingly became tenants.
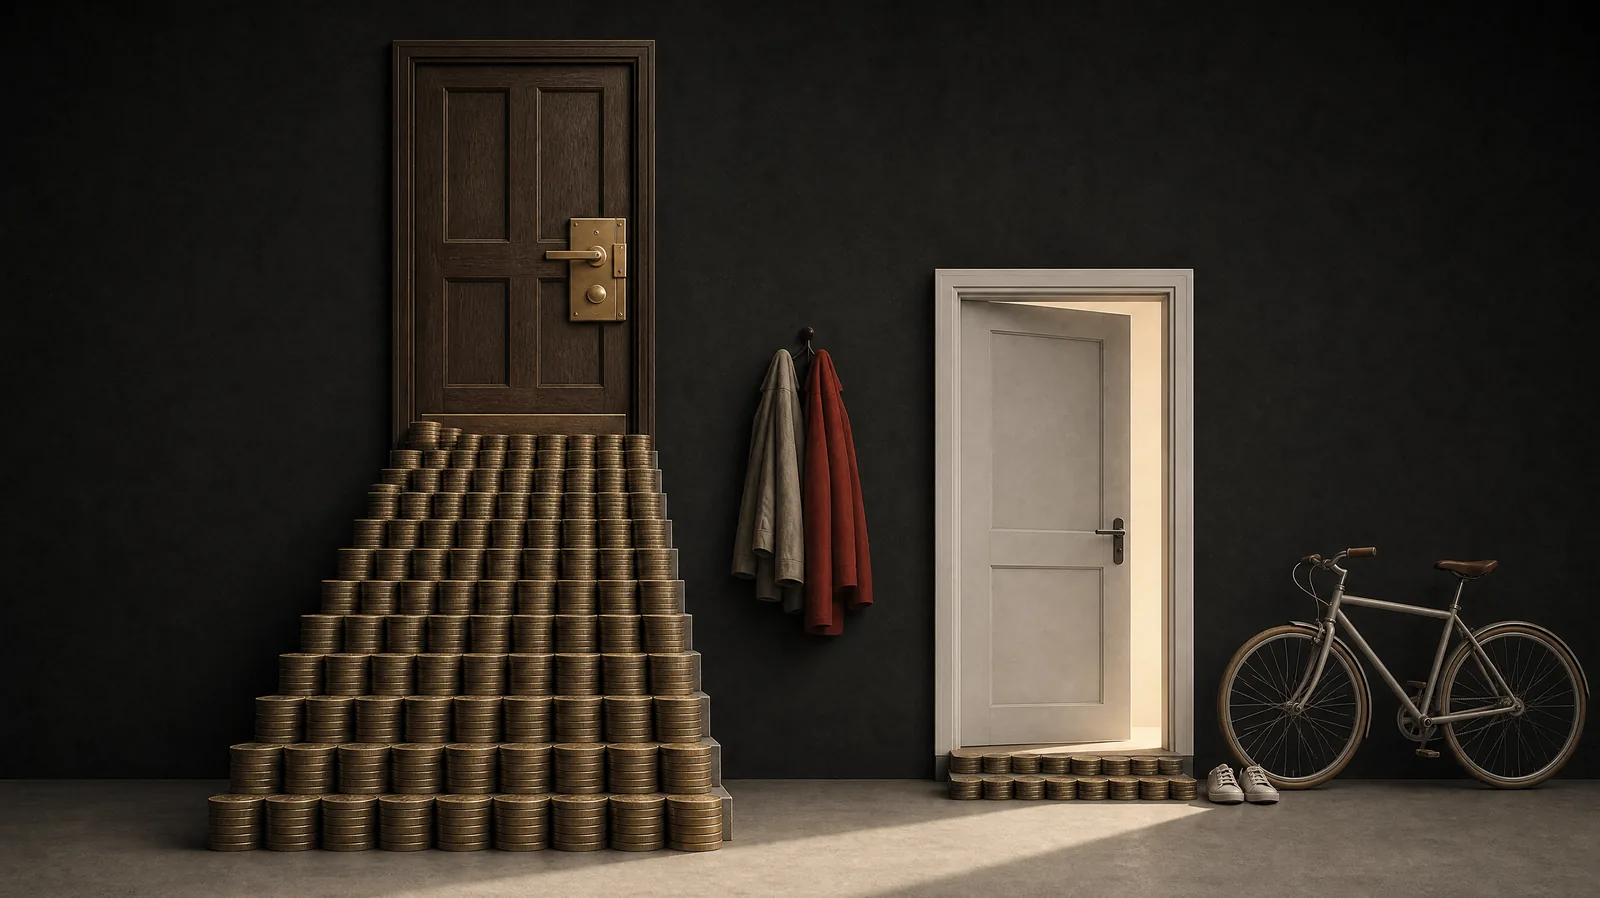 For a high-earning couple the rental door is a short step; the purchase door sits atop a towering stair.
The Next Two Years: Research Funding and Life Sciences Are the Real Near-Term Risk
On a two-year horizon, Boston's risk sits in life-sciences demand, but because homes cannot be built and owners will not sell, that risk shows up as continued core underperformance and thin volume rather than a broad price decline.
Does tight supply mean there is no risk over the next two years? No—the risk simply isn't on the supply side. 32.1% of Boston's jobs, about 795,000, are highly exposed to AI, above the national 28.6% (BLS OEWS and Eloundou et al., 2024). But AI is a ten-year variable, which I take up in the next section. On a two-year horizon, the larger and more certain risk is federal research funding and the life-sciences industry, because it directly determines where the core's buyers and renters come from.
Start with the money. By fiscal year, according to NIH's official RePORTER database, NIH funding flowing to Massachusetts peaked at $3.99 billion in FY2023 and fell to $3.67 billion in FY2026, 6.6% below FY2024, with 12.9% fewer funded projects (NIH RePORTER, FY2026). In the first half of 2025, 733 NIH projects in Massachusetts were terminated, affecting roughly $1.3 billion in unspent funds; Harvard alone had $2.3 billion in federal funding frozen (GBH News, June 2025, citing Grant Watch). Some was restored through litigation, but research institutions have broadly slowed hiring and expansion. For completeness: the Boston Globe, counting by calendar year, reports Massachusetts received $3.41 billion in 2025, only 1.4% less than 2024—a different accounting basis, but the same direction.
 When the federal research reservoir drops and lines are clamped, the labs and jobs that depend on it wilt first.
Then the people. International students are the entry point for both core rental demand and the future high-wage workforce. In fall 2025, new international enrollment nationwide fell 17% (IIE Fall Snapshot, 2025); Boston University's international graduate enrollment fell 10%, and UMass Boston's new international students fell 17% (GBH News, November 2025). Then the space: too much lab space was built during the pandemic, and when financing tightened, much of it emptied. In the third quarter of 2026, CBRE put Greater Boston lab vacancy at 28.9% and availability at 33.1%, with negative net absorption of 168,000 square feet and availability in mid-Cambridge at 59.3% (CBRE, Q3 2026); Savills measures 28.1%, and the 21.2% second-quarter figure from Lincoln Property has been overtaken by worse data.
Employment has begun to reflect all of this. MassBio's annual industry report shows Massachusetts biopharma employment fell 3.1% in 2025 to 113,503, a loss of about 3,600 jobs, with R&D roles down 3.9% and only biomanufacturing growing, by 238—the first annual decline in the more than twenty years MassBio has tracked the data (MassBio Industry Snapshot, 2026). The contraction is concentrated in R&D and early-stage companies, which hits Cambridge and Somerville hardest. My two-year judgment: research funding and life sciences will keep core prices underperforming and volume low, but because no new homes are coming and owners aren't selling, a sharp metro-wide decline is unlikely.
| Metric | Data | Source and year |
|---|---|---|
| NIH funding to Massachusetts | $3.99B (FY2023) → $3.67B (FY2026), −6.6% vs. 2024 | NIH RePORTER, FY2026 |
| Terminated NIH projects | 733, ~$1.3B unspent | GBH News, June 2025 |
| New international students, U.S. | −17% | IIE, fall 2025 |
| Greater Boston lab vacancy | 28.9% (availability 33.1%) | CBRE, Q3 2026 |
| Massachusetts biopharma employment | 113,503, −3.1%, first decline in 20+ years | MassBio, 2026 |
The Next Ten Years: AI's Impact on Judgment-Based Jobs, and the 1988 Precedent
On a ten-year horizon, only one question determines Boston's prices: how many of today's 320,000 judgment-based jobs paying over $150,000 will still exist.
As noted, Boston's prices today rest on the high-income households already here. Quantify that group: about 320,000 jobs pay over $150,000, 13% of all employment, but their combined wages account for 27% of Boston's total payroll; the comparable share is 13.5% in Dallas and 12.1% nationally (BLS OEWS). Boston's home prices depend on high-wage white-collar workers at more than twice the national rate. Broken down by occupation group, management accounts for about 198,840 of those jobs, or 62%, at an average salary of $183,090; computer and mathematical occupations 56,510; physicians only 24,630, or 7.7%—less than one in ten. Add law, education, and engineering, and judgment-based occupations make up 88.8% of the total. What holds up Boston's prices is not nurses, not blue-collar workers, not ordinary university staff, but highly paid professionals who earn by analyzing and deciding.
 The whole price vault rests on a few gilded columns of high-paid judgment jobs, twice the national reliance.
These are exactly the jobs I expect the second wave of AI to hit hardest. The first wave replaced repetitive work; the second replaces judgment work. Pharma won't disappear, but it may need fewer scientists; universities won't disappear, but they may have fewer students and staff; finance, consulting, and law won't disappear, but the headcount required to do the same work will keep shrinking. In AI Is Reallocating High-Income Jobs I compared cities on this dimension, and Boston's high-wage job mix is among the most concentrated in judgment work. A natural objection: if Boston is this hard to build in, shouldn't prices hold even if jobs decline? No. What can't be built is new housing; not a single existing home disappears. The real effect of thin supply is to make prices acutely sensitive to demand—each 1% change in employment moves prices about 2.3%—and that amplifier works in both directions.
Boston has run this experiment before. In the 1980s its pillars were minicomputers and defense contracts. After 1988 the minicomputer industry collapsed and defense orders were cut; Massachusetts employment fell 11.1% (Karl Case's 2000 study counts 360,000 jobs lost from a base of 3.2 million, or 11.5%). Boston was just as hard to build in then. What happened to prices? Case-Shiller shows nominal prices fell 15.9% and real prices fell 30.3%; nominal prices took 8.1 years to regain their peak, real prices 12.8 years. Most striking, mortgage rates fell from 10.3% in 1989 to 7.3% in 1993—a full 300 basis points—and did not stop the decline. Lower rates let one buyer borrow a bit more; if the high-income jobs are gone, the buyer is gone.
Within two years, owners holding 3% mortgages won't sell and new homes can't be built, so even a hiring slowdown shows up mainly as lower volume. But within ten years, some share of today's 3%-mortgage owners must sell: retirement, job changes, relocation, divorce, death. Nobody holds forever. Who buys then? The households that can afford a $730,000 home today are those 320,000 high-wage jobs. My judgment: if judgment-based jobs decline by 30% over a decade, Boston prices are likely to end up 20% to 30% below their normal trajectory, and a meaningful real-terms decline is highly probable. This is not a claim that Boston becomes a declining city—Harvard and MIT will still be there. It is a claim that a city dependent on judgment-based high-wage jobs, with almost no new supply, has no cushion when demand contracts.
 Today's owners hold tight, but life events loosen the planks one by one—who will be there to catch them?
| Metric | Boston | Comparison | Source |
|---|---|---|---|
| Jobs paying over $150,000 | ~320,000 | Dallas 194,000 | BLS OEWS |
| Share of employment / share of total wages | 13% / 27% | Dallas 13.5%, U.S. 12.1% (wage share) | BLS OEWS |
| Judgment-based share of high-wage jobs | 88.8% | Physicians only 7.7% | BLS OEWS |
| Share of jobs highly exposed to AI | 32.1% (~795,000) | U.S. 28.6% | BLS OEWS; Eloundou et al., 2024 |
| 1988–1995 prices | Nominal −15.9%, real −30.3% | Massachusetts employment −11.1% | Case-Shiller; Case, 2000 |
Concrete Guidance for Buyers, Sellers, and Investors
For owner-occupants on a five-year horizon, Boston is still safe; for anyone planning to sell within a few years, the next two years are the window; for pure rental investment, the cash flow doesn't work and I don't believe in the long-run appreciation—it is not a good target.
Buyers first. If you are buying to live in and your horizon is five years, I consider Boston a relatively safe market: supply is so thin that a sharp decline within two years is unlikely. If you intend to live in the core long term, now is actually more reasonable than the past few years, because core prices have risen at roughly half the pace of core rents—Brookline prices +6.9% against rents +31.0%—meaning the relative price of owning versus renting has tilted toward buying. But if your reason for buying is "Boston will surely be worth more in ten years," I disagree. On whether long holding periods automatically equal safety, I made the case in Should You Time the Market?; 1988 Boston is the counterexample: 8.1 years to recover in nominal terms, 12.8 in real terms.
Sellers next. If you were already planning to sell in the next few years—retirement, relocation, kids grown—I think the next two years are a good window, and there is no need to hold out for a higher price. New listings at 79% of pre-pandemic levels and a 43-day median time to sale are liquidity a seller can use. Single-family homes in the suburbs and gateway cities remain in the strongest position; the roughly 60% gains in Lowell, Plymouth, and Wellesley have already priced in years of supply scarcity. Owners of core condos in particular should be clear-eyed: condos rose only 0.9% in the past year, and the opportunity cost of waiting now exceeds the potential upside.
 For owners already planning to sell, today's scarcity and liquidity are a window worth taking.
Finally, investors. A $725,639 single-family home renting for $3,500 to $3,650 a month yields a gross return of roughly 6% (Zillow ZHVI and ZORI, September 2026; about 5.8% at $3,500). After property tax, insurance, vacancy, maintenance, and management, the net return is 3.1%—against a current mortgage rate of 7.32% (Freddie Mac PMMS, October 2026). The cost of borrowing exceeds the property's net return by more than four percentage points. The old answer was that weak cash flow doesn't matter because long-run appreciation makes up for it. But if you accept my argument above, Boston's biggest ten-year risk is precisely long-run depreciation. The question I posed in Is a Rental With No Cash Flow Still Worth Buying? has a clear answer in Boston: the cash flow doesn't work and I don't believe in the appreciation, so a Boston rental today is not a good investment.
Here are my two-year scenario probabilities:
| Scenario | Probability | Trigger | Price path | Structural pattern |
|---|---|---|---|---|
| Base | 60% | Status quo continues | Modest gains of 0%–3% per year | Low volume; suburban single-family steady to slightly up; core condos underperform; core rents rise modestly |
| Upside | 20% | Research funding recovers, life sciences resumes hiring, mortgage rates fall below 6% | Gains of 3%–6% | Core transactions recover |
| Downside | 20% | Research funding and white-collar employment keep contracting, rates exceed 7.5% | Flat to −3% to −5% | Core condos lead the decline |
 The widest path ahead is modest gains with thin volume; brighter and darker routes each take a narrower share.
On a ten-year horizon, I am outright bearish on Boston: after inflation, a meaningful price decline is highly probable.
Counterarguments and Responses
The strongest objections to this analysis are "scarce supply always provides a floor" and "AI will create new high-wage jobs"—both have merit, and neither changes Boston's fragile structure.
Objection one: with supply this tight, prices can't fall no matter what demand does. This is the most common view and the one most worth taking seriously, and it is correct on a two-year horizon. But supply constraints limit new supply; they cannot stop the release of existing stock. The Boston metro has about 1.97 million households and adds roughly 10,000 new homes a year, but the number of existing homes that change hands each year through retirement, relocation, divorce, and death far exceeds new supply. Boston in 1988–1995 was just as hard to build in—the geographic and institutional constraints Saiz measures were already in place—yet nominal prices fell 15.9% and real prices 30.3%. The true function of scarce supply is to amplify demand changes: the regression shows each 1% change in employment moves Boston prices about 2.3%, versus near zero in Dallas. Amplifiers have no directional preference.
Objection two: AI will create new high-wage jobs, and Boston is the city best positioned to capture them. I agree AI will create new work, and Boston's universities and research institutions are genuine sources of innovation. But two things must be separated. First, whether the new jobs are numerous enough to replace the compressed ones—the second wave of AI is defined not by industries disappearing but by the same work requiring fewer people; pharma, law, finance, and consulting will all continue, with fewer analysts and scientists. Second, whether the new jobs land in Boston. As I argued in The 24 U.S. Cities That Benefit in the AI Era, what drives home prices is wages, not capital expenditure, and current data do not show Boston absorbing new high-wage jobs: information employment is 14.8% below end-2019, professional and technical services 0.9% below, and biopharma employment posted its first annual decline in more than twenty years in 2025. If new jobs materialize, they will appear in the employment data, not in expectations.
Objection three: your two-year and ten-year views contradict each other—you say supply provides a floor, then predict a big decline. There is no contradiction; the same mechanism behaves differently on different horizons. Within two years, price is determined by whether anyone sells; owners holding 3% mortgages don't, and new homes can't be built, so prices are resilient. Within ten years, price is determined by whether anyone buys; some share of rate-locked owners will sell due to life-cycle events, and then the number and income of the buyers who show up decide the outcome. That is exactly what happened in Boston after 1988: volume vanished first, then prices followed. Both judgments rely on the same data and the same transmission mechanism; they simply watch different variables.
 Two years hinge on who sells, ten on who buys—one mechanism showing two faces across time.
Objection four: rates will fall, and rate cuts will rescue prices. From 1989 to 1993, Boston mortgage rates fell from 10.3% to 7.3%, a 300-basis-point drop, and prices still fell. Rates determine how much one buyer can borrow; employment determines how many buyers there are. In a market with a supply elasticity of 0.86, the second variable carries far more weight than the first.
Method Summary: How to Judge a City's Home Prices
Judging a city's home prices requires looking at demand and supply together and at two years and ten years separately; these eight questions apply to any city.
There are two methods I most want readers to take from this research. First, flat employment does not mean prices must fall. Dallas has strong demand, but builders build faster, so prices stall; Boston has flat demand, but almost no new homes, so prices don't fall. Looking at demand alone or supply alone yields the wrong conclusion for both cities. Second, a two-year trend does not predict a ten-year trend. Within two years, price is determined by whether anyone sells; within ten years, by whether anyone buys. Expanding those two methods produces the following checklist.
 Only with demand and supply layered together—and two years separated from ten—does a city's true shape emerge.
Four demand-side questions:
- Is total employment growing, flat, or shrinking? By industry, are high-wage or low-wage sectors doing the growing? (Sources: BLS QCEW, CES)
- What are the level and growth rate of the existing wage base? What share of employment and total wages do high-wage jobs represent? This determines how much support incumbent owners can provide. (BLS OEWS)
- What is the income profile of in-migrants versus out-migrants? Are buyers or renters leaving? (IRS SOI migration data, Census Population Estimates)
- How large is the gap between local median household income and the income required for the median home? What is the monthly cost gap between owning and renting? (Zillow, Census ACS, Freddie Mac)
Two supply-side questions: 5. What is the housing-supply elasticity? How many permits are issued relative to households and population? (Saiz 2010; Census BPS) 6. How rate-locked are existing owners? Where are new listings and active inventory relative to pre-pandemic levels? (Realtor.com)
Two time-horizon questions: 7. Within two years, who will sell? If no one does, price resilience comes from illiquidity rather than demand—watch volume, not price. 8. Within ten years, who will buy? What share of the jobs that carry prices are judgment-based, and how exposed are they to AI? Does the city have a historical demand shock to use as a reference?
Run Boston through these eight questions and the conclusion follows: three demand-side weaknesses, two extremely tight supply-side constraints, supply decides the two-year picture, demand decides the ten-year picture. Next up is San Diego—its supply elasticity is only 0.67, even harder to build in than Boston, and its prices have risen more, but the problem it faces is entirely different.